
Unbiased headlines. Facts, not spin.
Unbiased Headlines is an independently owned news organization. We bring you the facts, not opinions, written fresh from 110+ named sources. Sources linked so you can verify it yourself.
 economy
Notable (5/10)
Global Pension Index Grades US Retirement System C+, With Sustainability Score Down to 57.1
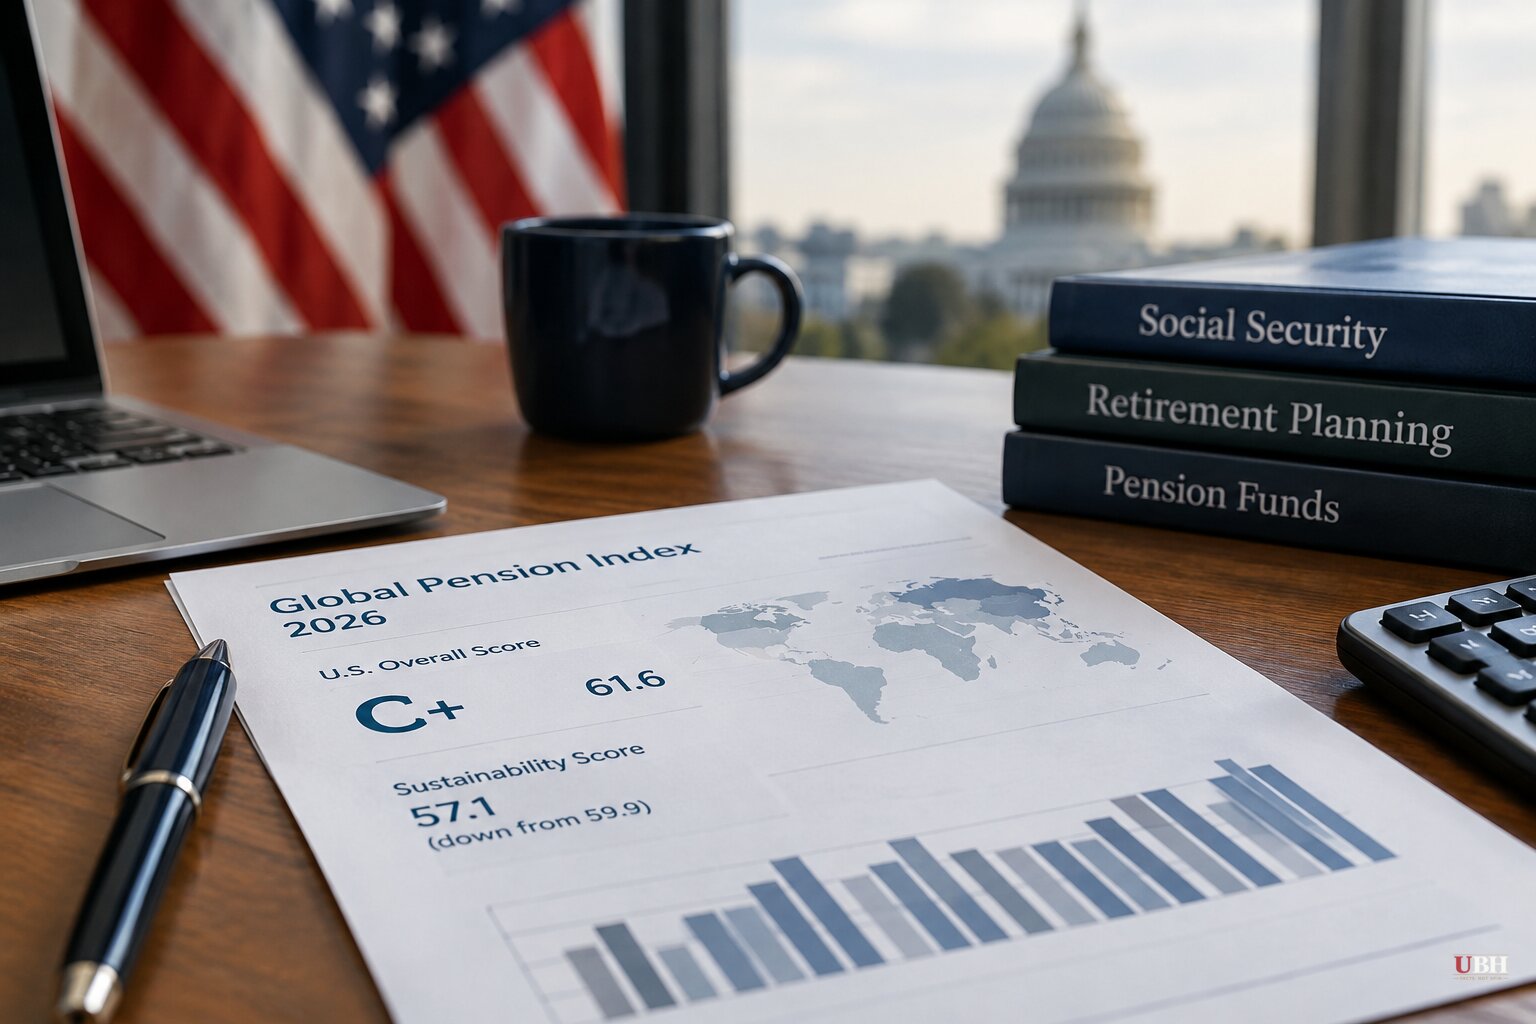
The United States earned a C+ in the 2026 Marsh CFA Institute Global Pension Index, released Tuesday, Oct. 20. That put it below more than two dozen peer nations.
The U.S. scored 61.6 overall, up from 61.1 last year. Its sustainability score fell to 57.1 from 59.9.
The 18th annual index, produced by Marsh and CFA Institute with the Monash Centre for Financial Studies in Melbourne, compares 55 retirement systems covering about 66% of the world's population. It grades each on adequacy, sustainability and integrity.
Who scored at the top
The Netherlands led at 85.8, followed by Denmark at 84.1 and Iceland at 84.0. Australia reached the A tier for the first time, at 80.6.
The six A-grade systems are the Netherlands, Denmark, Iceland, Singapore, Israel and Australia. According to the index, they share near-universal coverage, strong governance and funded structures that do not rely only on pay-as-you-go financing.
The index defines a C+ as a system with "some good features but also major risks and shortcomings" whose long-term effectiveness and sustainability "can be questioned."
The U.S. leans heavily on Social Security, which is pay-as-you-go, plus voluntary 401(k) and 403(b) plans. Those plans leave significant portions of the workforce with no employer-sponsored savings vehicle.
The demographic math
This year's report includes a chapter on aging. Of the 55 systems covered, 43 have fertility rates below the 2.1 children per woman needed to replace a population. Twenty-three are below 1.5.
Life expectancy at age 65 in more developed regions is up 50.9% since 1950, to about 20 additional years. The number of potential workers supporting each older person is set to fall sharply.
"The funding of future pensions and aged care both become more critical as the ratio of workers to retirees continues to decline," the report states. "Very few systems, as they currently operate, are secure."
Pay-as-you-go systems are the most exposed. Today's workers largely fund today's retirees, so a shrinking workforce hits them directly.
The U.S. example is specific. The Old-Age and Survivors Insurance Trust Fund, which pays retirement and survivor benefits to tens of millions of Americans, is projected to exhaust its reserves in the fourth quarter of 2032, according to the latest Social Security trustees' report.
Funded plans are not immune
Fully funded systems face their own problem. As members retire and start drawing down, some funds could pay out more than they take in from new contributions. The index says that forces a rethink of investment strategy and liquidity needs.
Sebastien Betermier, executive director of the International Centre for Pension Management, called the problem "huge, and it's gotten more pronounced over time." He told CNBC some pension funds have members who have been retired for nearly half a century, aged 107 or 108.
"The higher the longevity, the more years the pension funds have to cover, and so that immediately comes in as an additional liability," Betermier said. "Think about the cost that it imposes actually on the next generation … it is a ticking time bomb."
Defined-benefit plans, which promise a set income, carry growing liabilities as retirees live longer. Defined-contribution plans, where payouts depend on savings and returns, put the longevity risk on the individual, who may outlive the account.
Jean-Pierre Aubry of the Center for Retirement Research at Boston College described where that risk is landing. "Everybody is shifting a little more risk where they can," he said. "The costs are going up with this demographic shift."
What the authors want done
The index recommends three policy responses. Governments should set clear objectives for their pension systems, prioritize funding future obligations, and build flexibility into product design and retirement ages.
The report says traditional retirement ages of 60 or 65 are "increasingly misaligned" with longer, healthier lives. It also points to the blurring line between work and retirement, driven partly by gig and part-time work.
"The time to act is now," said Pat Tomlinson, president and CEO of Marsh People and Investments. Christine Mahoney, the firm's global defined benefit and defined contribution leader, said governments that "clarify their pension objectives, strengthen funding, and build flexibility into retirement design will be far better positioned."
Mona Naqvi, managing director of the CFA Institute Research and Policy Center, said no single policy or investment decision can solve the problem. She stressed "careful oversight of investments by those with a fiduciary duty to savers and retirees."
Those are the prescriptions of a consulting firm and an investment-industry association, both of which advise on funded retirement products. The index's rankings, though, are drawn from measurable system features rather than opinion.
What comes next
The date that matters for U.S. retirees is the fourth quarter of 2032, the trustees' projection for when the OASI reserves are gone. That is about six years from today, Oct. 25, 2026.
The index does not say how Congress should close the gap. It says only that systems relying on pay-as-you-go financing are the least secure.
Sources used for this briefing
7 links from 3 independent newsrooms (syndicated copies of the same report count once)
These are the sources it draws on, linked so you can verify.


