
Unbiased headlines. Facts, not spin.
Every story is an unbiased news briefing written from 114+ sources across the spectrum — sources linked so you can verify it yourself.
 economy
Notable (6/10)
Event date: October 1, 2026
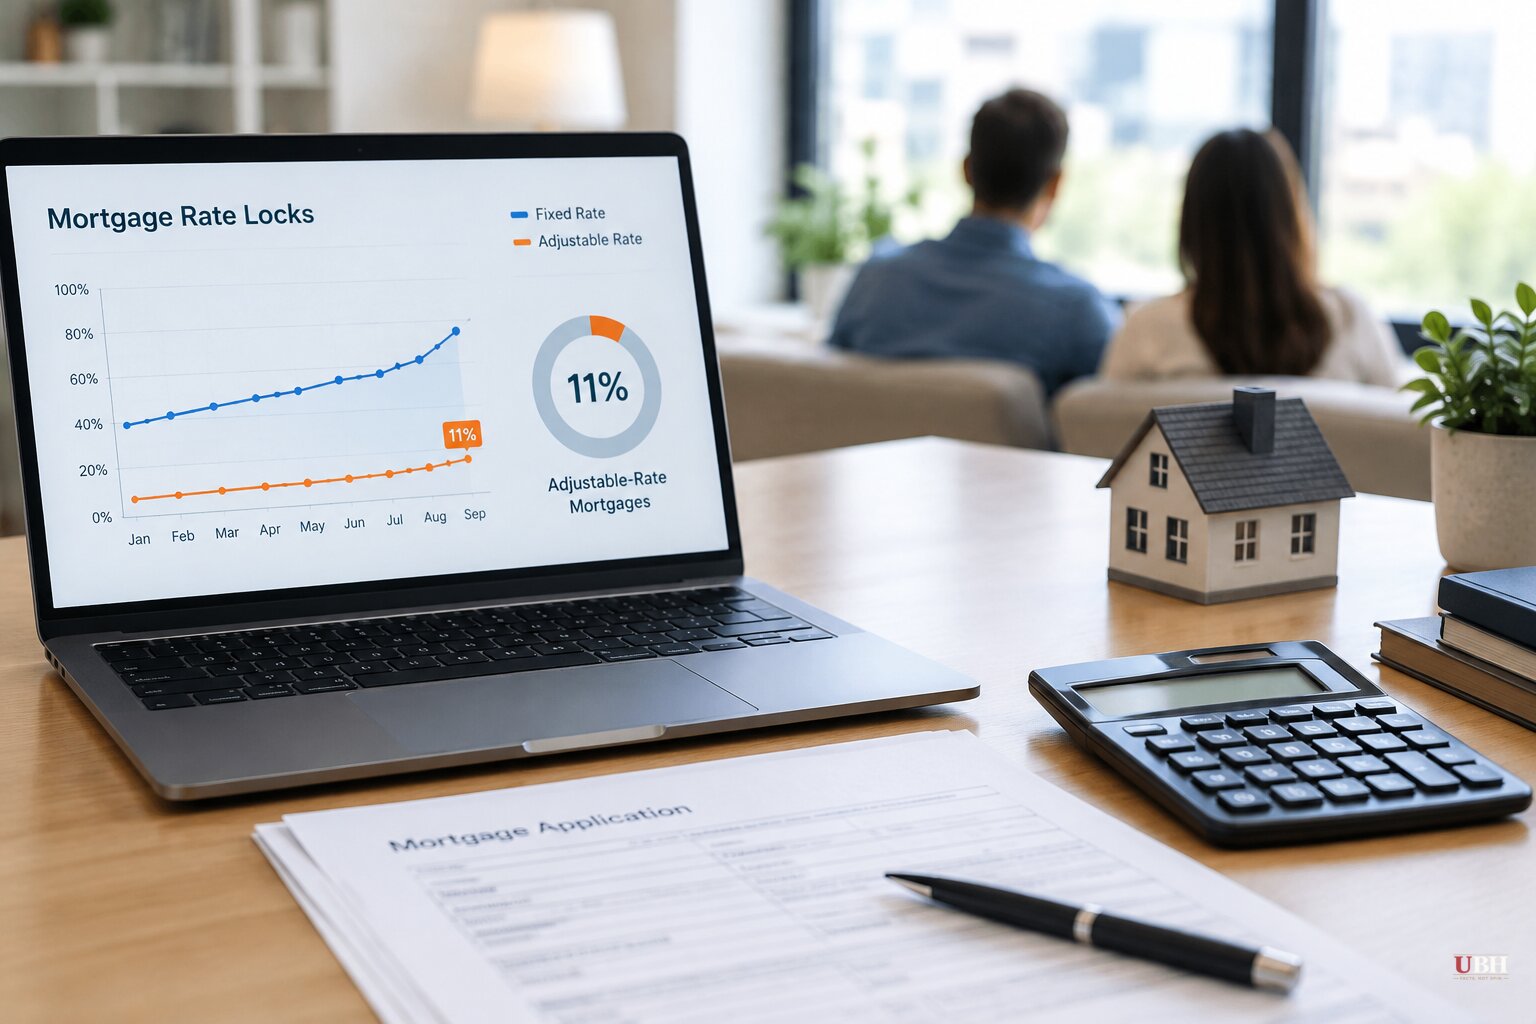
Adjustable-Rate Mortgages Reach 11% of Rate Locks as Fixed Rates Climb, and 186,000 Borrowers Face First Resets in 2027
Since late February, when the average 30-year fixed rate briefly fell to 5.98%, borrowing costs have climbed about a full percentage point, and buyers are now reaching for a riskier product to blunt the hit: the adjustable-rate mortgage.
Nearly 11% of first-lien mortgage rate locks in the week ending Sept. 18 were ARMs, according to the ICE Mortgage Monitor. Among purchase buyers alone, almost 9% chose an ARM, the second-highest weekly share since 2022.
The reset math
There are 3.1 million active first-lien ARMs nationwide, the most in about five and a half years, ICE says. Most have not started adjusting.
ICE projects about 186,000 homeowners will see their ARM reset for the first time in 2027, up from 148,000 this year. The median borrower in that group faces a rate jump of roughly 2.2 percentage points. That means a $645 increase, or 24%, in the monthly payment.
People who took seven-year ARMs in 2020 face the worst exposure. For the median borrower in that cohort, ICE estimates the rate goes from 2.75% to 5.79% at the first reset. The payment rises by more than $1,000, or 36%.
Why buyers are doing it
Bond market pressure is driving the shift. Freddie Mac's weekly survey put the 30-year fixed at 7.28%, up from 7.03% a week earlier, and ICE's own daily index ended September at 7.31%, its highest since November 2023. ICE says rates have risen seven straight months, up 136 basis points from the February low of 5.95%.
The 10-year Treasury yield is around 5.3%, up from 3.97% in late February before the U.S. and Israel attacked Iran. Higher oil prices and inflation fears have driven the move. Epoch Times reports the Federal Reserve raised rates a quarter point in September and that investors expect another increase in late October.
Mortgage News Daily's tracker, a different gauge, showed almost 7.5% on Sept. 25. Its chief operating officer, Matthew Graham, said 7% was first broken on Sept. 10 after inflation reports raised the odds of the Fed hike.
Buyers are also paying to buy down rates. More than half of purchase borrowers paid at least half a point upfront in August, and more than a third paid at least a full point. ICE's affordability math still shows the median-priced home with 20% down costing $2,383 a month in principal and interest. That is 31.7% of median household income, the worst reading in nearly two years.
The case that the risk is contained
ICE's own analyst argues the problem is limited. "ARMs are becoming more attractive to borrowers looking for relief from today's higher fixed rates, but the overall market exposure to adjustable payments remains relatively limited," said Andy Walden, ICE's head of mortgage and housing market research. ARMs are 5.6% of active mortgages.
Freddie Mac chief economist Sam Khater said the housing market "remains supported by a solid labor market and an economy that is growing at a healthy rate." Philadelphia mortgage banker Patrick Lopez of Quaint Oak Mortgage tells buyers that waiting for 5% rates is a losing game, because prices tend to rise and a rate drop would flood the market with competing buyers.
Lawrence Yun, chief economist at the National Association of Realtors, said to "expect 7% as the new normal." Existing-home sales fell 2% in August to a 3.98 million annual pace, and mortgage applications dropped 6% in the latest weekly reading.
Canada faces the same renewal wall
The pattern is not limited to the U.S. Canada's five-year government bond yield has climbed to about 3.7%, more than triple the sub-1% levels when millions of Canadians took five-year fixed mortgages in 2020 and 2021. The 10-year Government of Canada yield rose to 3.99% from 3.45% at the start of July. The Bank of Canada's overnight rate has held at 2.25% since October 2025.
The C.D. Howe Institute says renewing households face "higher payments, raising concerns about household finances and financial system stability." About 33% of Canadian mortgage holders are expected to face higher monthly payments by the end of 2026. Among those renewing variable-rate mortgages, 10% are projected to see increases above 40%.
Equifax Canada's Q1 2026 data show mortgage delinquency balances up 32% year over year nationally and 52% in Ontario. Ratehub.ca lists the lowest insured five-year fixed rate as of Oct. 7 at 4.34%. Aled ab Iorwerth, CMHC's deputy chief economist, says rising yields, inflation worries and trade uncertainty are making the rate and housing outlook hard to predict.
What comes next
The U.S. exposure is still mostly ahead. The 2027 reset class of 186,000 borrowers, and the 2020 seven-year ARM holders within it, will show whether the product choice buyers are making now turns into delinquencies. The next test is the Fed's late-October meeting, where investors expect another hike.
Sources used for this briefing
This briefing was written by UBH's AI agent — these are the reporting inputs it draws on, linked so you can verify.


