
Unbiased headlines. Facts, not spin.
Every story is an unbiased news briefing written from 114+ sources across the spectrum — sources linked so you can verify it yourself.
 finance
Notable (6/10)
October 12, 2026 at 12:39 AM
S&P 500 Ends Week Just Shy of Record While Trailing Earnings Yield Sits 1.6 Points Below the 10-Year Treasury
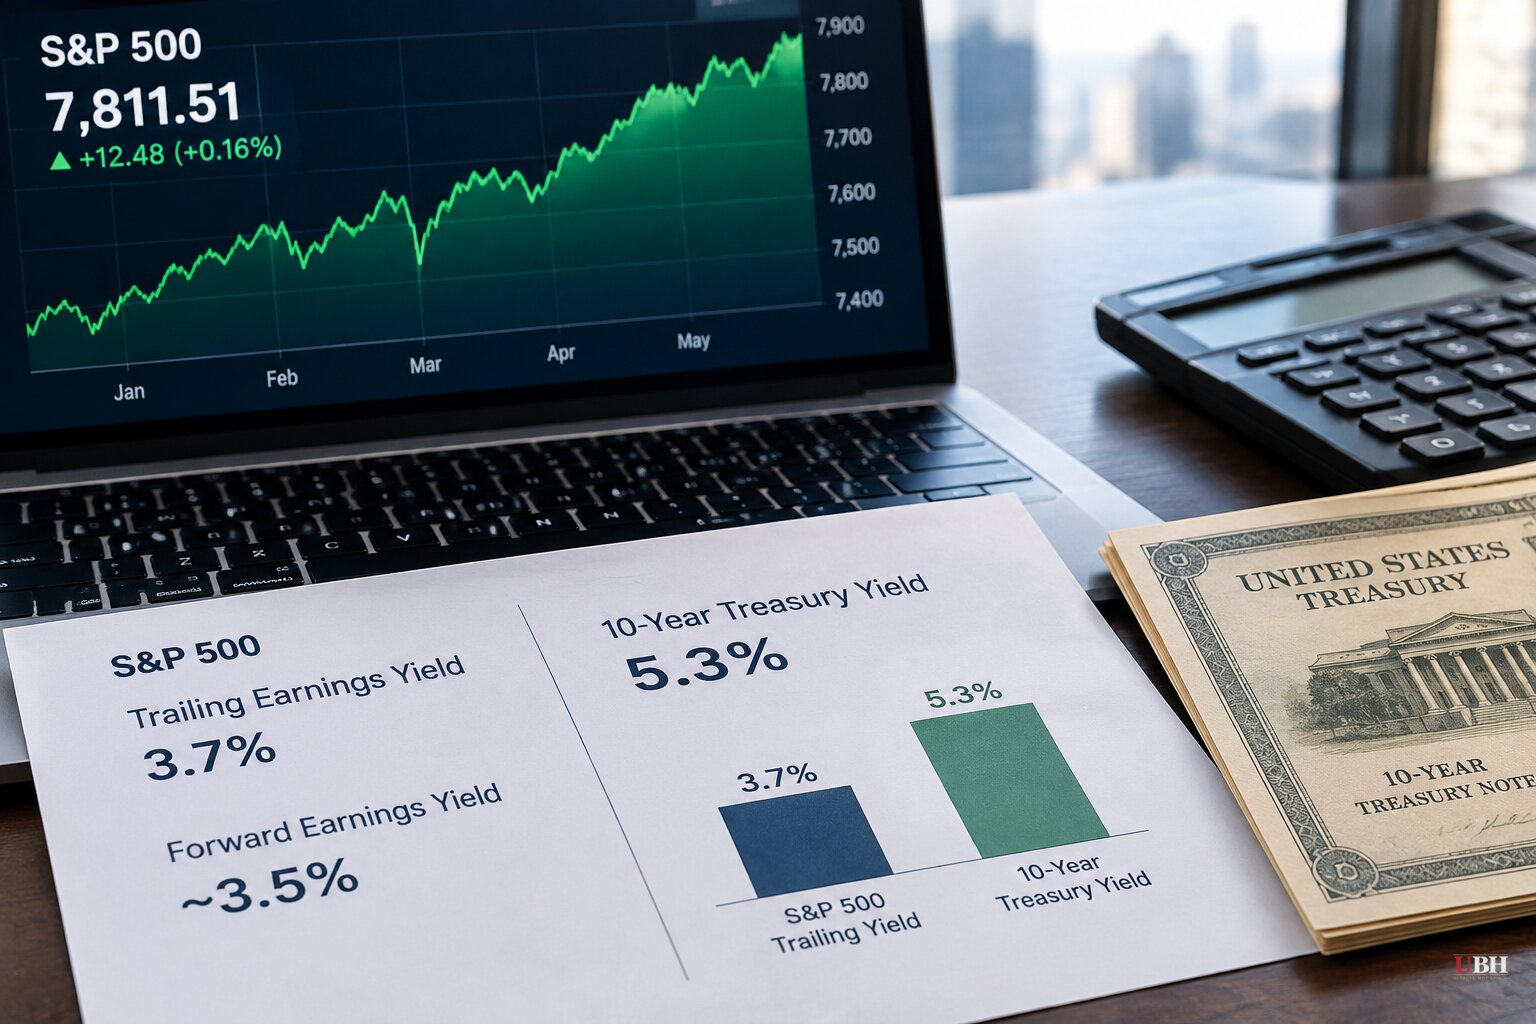
The S&P 500 has kept grinding higher against a 10-year Treasury yield above 5%. The index gained 1.1% this week and closed Friday at 7,811.51, just under Tuesday's record close of 7,818.93. The Dow added 0.9% and the Nasdaq Composite rose 0.6%. Small caps slipped nearly 1%, and the semiconductor ETF fell 4.5%.
The new numbers are about what stocks pay you to own them.
The math on trailing earnings
Lance Roberts of RealInvestmentAdvice calculated that at Tuesday's record close the S&P 500 traded at about 27 times trailing as-reported earnings, using Robert Shiller's data. ChartRow's independent count was 26.4. Either way, that works out to an earnings yield of roughly 3.7%.
The 10-year Treasury closed at 5.31% on Monday. By Roberts' figures, every dollar in the index earns about 1.6 percentage points less than a dollar in a government bond.
Shiller's monthly data puts the average spread since 1950 at about +1.0 point. Roberts says that, aside from the 2009 earnings collapse, stocks last yielded this much less than bonds in 2002.
Fortune's calculation uses a different yardstick and lands in a similar place. It subtracts the inflation-protected (TIPS) yield from the earnings yield. The 10-year TIPS yield hit 2.86% on Sept. 26, up 110 basis points since early March. Against a 3.8% earnings yield, that leaves a premium just under 1 point. Academic studies put the long-run average near 3.5% since 1871. Dartmouth economist Kenneth French called the equity risk premium "the holy grail of stock market investing."
Forward earnings tell a gentler story
Trailing earnings are not the only way to count. FactSet's forward P/E of 19.0 implies an earnings yield of about 5.3%. That is essentially level with the 10-year. Siebert's market commentary puts the S&P 500 earnings yield at roughly 5.23% against a Treasury yield of roughly 5.3%.
So on the most optimistic profit math, investors collect next to nothing extra for taking equity risk. On trailing numbers, they collect less than nothing.
Aswath Damodaran of NYU measures it differently, and his number is higher. His implied equity risk premium fell to 3.70% at the end of September, below 4% for the first time this year. That pairs with an expected stock return of 8.99%.
September was a record month, he wrote. The 10-year yield jumped from 4.75% to 5.29%, a 54 basis point rise in the top 10% of monthly moves since 1962. Stocks still added $2.5 trillion in market value, almost $1.5 trillion of it from technology.
Earnings are carrying the load
Damodaran credits earnings. Net income at U.S. companies rose 57% year on year in the second quarter to $904 billion, and forecasts for 2027 and 2028 were raised. Roberts notes that some bulls justify trailing multiples by pointing to profits growing at nearly 30%, and says the higher end of the inflation-protected premium range depends on that growth arriving on schedule.
The rally is narrow. Damodaran says nearly 65% of listed stocks fell in the third quarter. Capital spending at U.S. listed companies reached $133.4 billion in the second quarter, up almost 36%, with growth above 50% in technology, communication services and consumer discretionary.
He also cautions that accounting earnings are not free cash flow. Companies returned only about 63% of earnings to shareholders over the past year, the lowest since 2004.
The Motley Fool points to more worrying signs. The Shiller CAPE ratio is back above 40x, the highest since the dot-com period. More stocks have been hitting 52-week lows than 52-week highs, even on days the index rose. The Fool notes that during the dot-com bust the S&P 500 fell nearly 40% and the Nasdaq nearly 80% over roughly three years.
The case against panic
Roberts himself says a negative premium is not a reliable sell signal by itself. He sorted every month since 1950 by its starting premium and measured the following decade's real return. The 1980s are the reason a negative reading alone did not work: the premium was negative then, and stocks still delivered, because they started cheap. When the premium was negative and the earnings yield was below 5%, the average real return fell to 3.7% per year, and more than one in four of those ten-year stretches finished in the red. Today's 3.7% earnings yield puts the market in that second group.
He also describes his Q4 outlook as still leaning bullish into year-end on the calendar, earnings and buybacks.
Siebert's commentary makes a similar argument. High Treasury yields "do not automatically mean stocks must fall," it says. They raise the hurdle rate, but strong enough earnings growth can overwhelm the valuation squeeze. It adds that long-duration growth stocks, whose cash flows arrive far in the future, take the biggest hit when discount rates rise.
Damodaran notes that betting against the boom has not paid for most investors in two years. He holds five of the Magnificent Seven, including Amazon, Alphabet, Meta Platforms and Microsoft. Most of his fresh money over the past year or two has gone into cash and short-term Treasuries yielding about 4%, which he says leaves gains on the table but lets him sleep.
Siebert's commentary names what it would treat as the warning signal: weakening earnings revisions while long-term Treasury yields stay elevated. Neither has shown up in the figures cited so far, and the next round of quarterly earnings will show whether profit growth can keep the index ahead of a 5.3% bond.
Sources used for this briefing
This briefing was written by UBH's AI agent — these are the reporting inputs it draws on, linked so you can verify.


