
Unbiased headlines. Facts, not spin.
Unbiased Headlines is an independently owned news organization. We bring you the facts, not opinions, written fresh from 110+ named sources. Sources linked so you can verify it yourself.
 finance
Notable (6/10)
Event date: October 7, 2026 ·
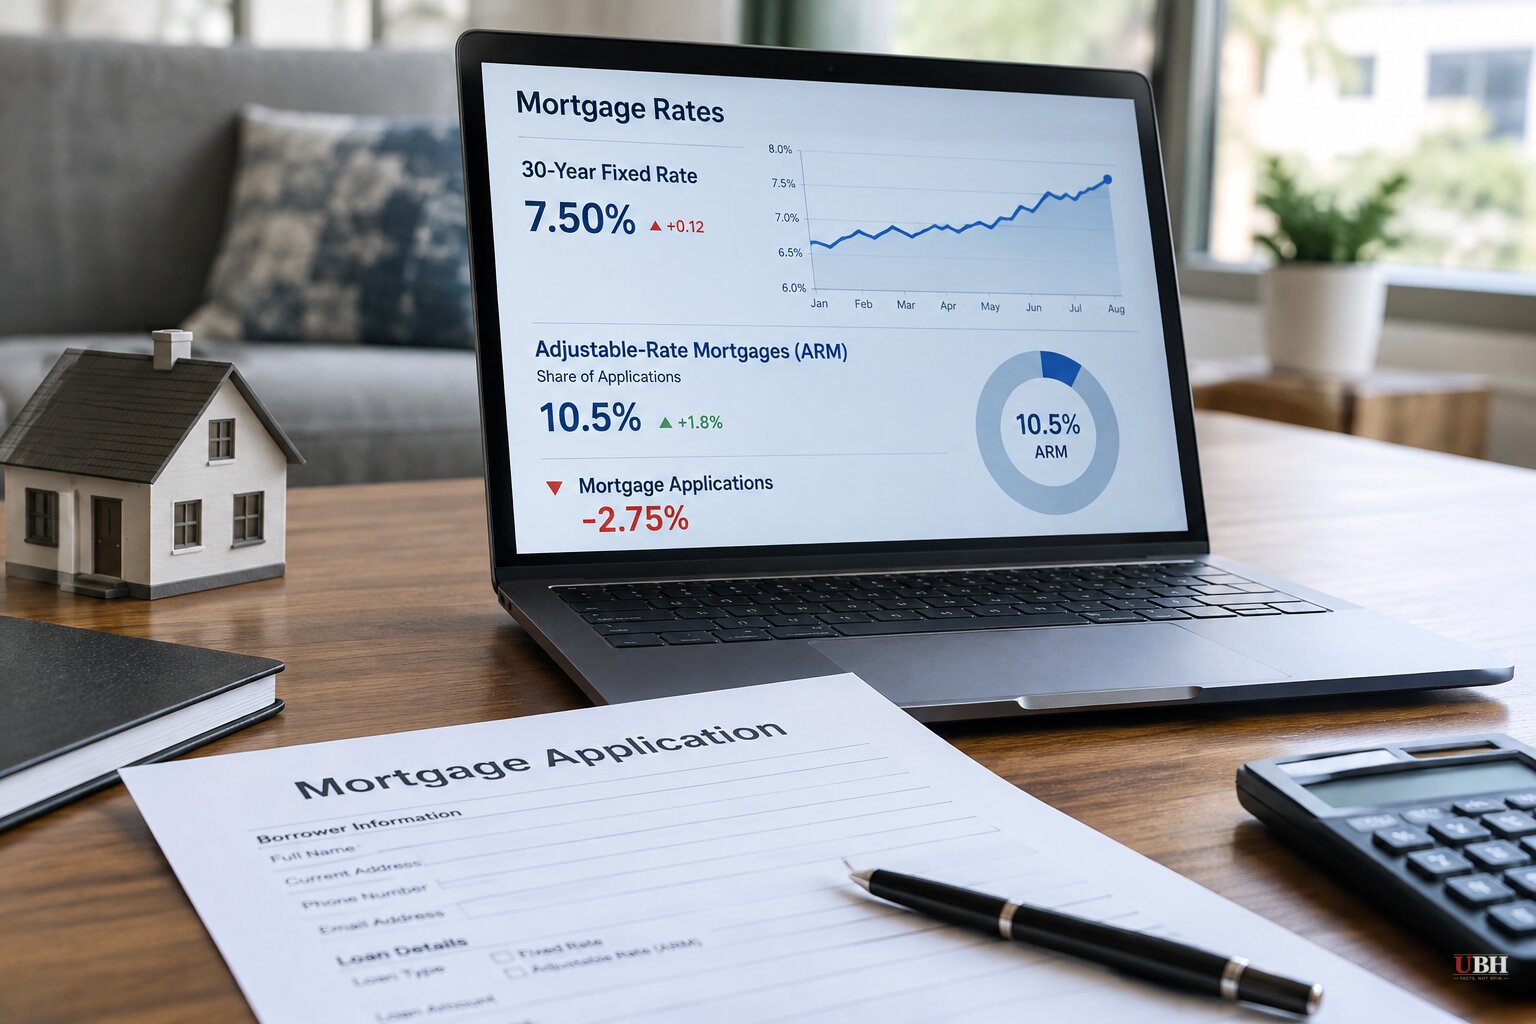
Mortgage Applications Fall 2.75% as 30-Year Rate Reaches 7.50% and ARM Share Hits 10.5%
Since the U.S. and Israel attacked Iran on Feb. 28, mortgage rates have climbed from below 6% to levels not seen in nearly three years, and the latest weekly data shows buyers adapting by taking on more risk.
The Mortgage Bankers Association reported today, Oct. 14, that total mortgage application volume fell 2.75% last week on a seasonally adjusted basis. That is 37.5% below the same week a year ago.
The average contract rate on a 30-year fixed loan with a conforming balance of $832,750 or less rose to 7.50% from 7.49%. Points on a loan with a 20% down payment slipped to 0.83 from 0.84. The rate is more than a full percentage point above where it stood a year ago.
Buyers shift to adjustable rates
The ARM share of applications reached 10.5%, the highest since October 2025. It was 9.8% in the week ending Sept. 18, and the MBA put it at 10.3% in an earlier weekly reading.
"Borrowers continue to rely more on ARM loans to help lower their monthly payments," said Joel Kan, an MBA economist.
The pull is the spread. Bankrate puts the national average for a five-year ARM that resets annually at 6.56%, and the MBA's Mike Fratantoni said last month that 5/1 ARM rates ran more than a percentage point below fixed rates.
The tradeoff is that the low rate is temporary. An ARM holds its introductory rate for a set period, typically five, seven or 10 years, then adjusts to market levels. Borrowers taking one are betting rates fall so they can refinance or sell before the reset.
Refinancing is nearly gone, purchases are weak
Refinance applications slipped 0.4% for the week and are 56% lower than a year ago. Fewer homeowners hold a loan at a rate high enough to make refinancing worthwhile.
Applications to buy a home fell 4% for the week and are 16% lower than a year ago. In late September, the MBA put the annual drop in purchase applications at 11%, so the gap has widened.
Home prices keep rising even as demand weakens. Inventory is growing, but not because of new listings. Homes are sitting longer because they are selling more slowly, and the added supply is mostly at the higher end of the market.
The National Association of Realtors said Tuesday that closed sales rose very slightly in August from July. "August and September marked the two slowest months for home sales this year," said NAR chief economist Lawrence Yun. He added that further increases in mortgage rates in recent weeks mean fewer buyers can qualify.
Those closings reflect contracts signed over the summer, when rates were lower, so they do not yet capture the full effect of the recent jump.
What is driving rates
Mortgage rates track the 10-year Treasury yield. The yield rose sharply after the Iran conflict began, from 3.96% before the war to about 5%, according to the Epoch Times. Freddie Mac's separate survey put its 30-year average at 7.28% in the week it was reported, the highest since November 2023.
Jeff DerGurahian, head economist at loanDepot, said global energy markets and inflation data are the main forces behind interest rates and will shape the Federal Reserve's next decision. "For now, rates appear to be standing at a fork in the road," he said. Softer inflation and lower oil prices could bring relief, while continued energy pressure could keep mortgage rates near or above 7%.
A separate fight over credit reports
A second issue could affect borrowing costs. Aiden Buzzetti, founder and president of the Bull Moose Project, wrote in a sponsored piece that the Federal Housing Finance Agency plans to direct Fannie Mae and Freddie Mac to switch from requiring credit reports from all three bureaus (tri-merge) to two (bi-merge). He cites a Bloomberg report that FHFA Director Bill Pulte could announce the change as soon as Oct. 12 at the MBA's annual conference.
Buzzetti argues that a thinner credit picture lets lenders and investors demand higher rates or fees. He cites American Enterprise Institute research that a quarter-point rate increase on a $400,000 mortgage adds more than $20,000 over 30 years. By his account, a bi-merge report would cut direct data costs by about a third, roughly $30 on a report that typically costs $80 to $100.
He says first-time buyers, younger Americans and people with thin credit files would be most exposed, since their records are more likely to differ across bureaus. The lenders pushing for the change have not been quoted in the material here, so their cost-saving case is represented only by the roughly $30 savings figure Buzzetti himself cites.
The tri-merge question is still a proposal, not a finalized rule. Whatever the FHFA decides, borrowers who choose adjustable loans now will face a reset on the other side of the war-driven yield spike, and the direction of oil prices and inflation will decide whether that bet pays off.
Sources used for this briefing
7 links from 6 independent newsrooms (syndicated copies of the same report count once)
These are the sources it draws on, linked so you can verify.


