
Unbiased headlines. Facts, not spin.
Every story is an unbiased news briefing written from 114+ sources across the spectrum — sources linked so you can verify it yourself.
 economy
Notable (5/10)
Event date: October 9, 2026
French Assembly Committee Backs Tax on Crypto-to-Stablecoin Swaps and €800,000 Crypto Exit Tax
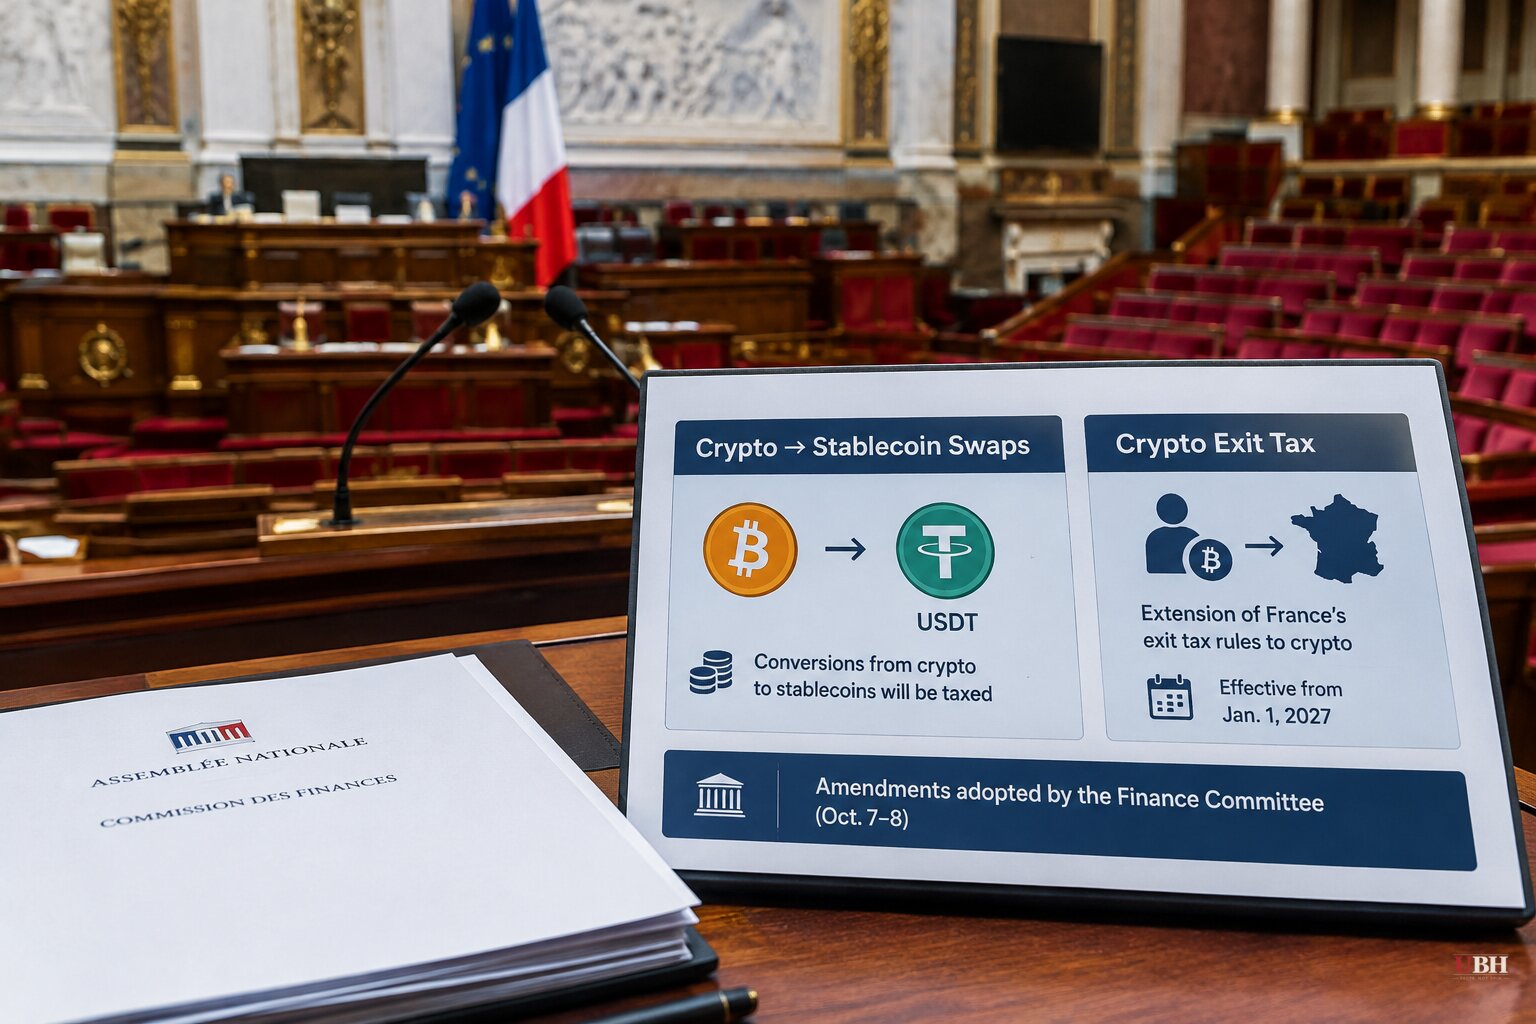
France's National Assembly Finance Committee has approved a package of crypto tax amendments to the 2027 budget bill. One would turn swaps of crypto into stablecoins into taxable sales. Another would extend the country's exit tax to crypto holders who move abroad.
These are committee votes on a budget bill, not law. The full Assembly begins examining the 2027 Finance Bill on Tuesday, Oct. 13.
Stablecoin swaps would become taxable
Amendment I-CF1826 was adopted on the evening of Oct. 7. It was submitted by Nicolas Sansu and sixteen other deputies from the GDR group.
Today, an investor can swap Bitcoin or Ether for a euro- or dollar-pegged stablecoin without triggering tax, as long as the gains are not converted into euros. The 31.4% flat tax applies when the investor sells for fiat currency.
The amendment targets electronic money tokens as defined under the EU's Markets in Crypto-Assets (MiCA) regulation. That covers stablecoins backed by an official currency. Conversions into those tokens would be taxed as disposals from Jan. 1, 2027.
The sponsors call the current treatment a "loophole in legislation" that deprives the state of revenue. Their explanatory statement argues that stablecoins can be used for payments and for buying other crypto, so converting into one is not meaningfully different from cashing out.
The mechanics are spelled out. Gains would be calculated as the difference between the disposal value and the acquisition cost, with documented transaction expenses deductible. For crypto bought before Jan. 1, 2027, taxpayers could either use documented purchase prices or allocate their portfolio's total acquisition cost as of Dec. 31, 2026, across the assets then held. The portfolio method is an irrevocable election made on the first tax return covering a taxable disposal.
Crypto-to-crypto swaps with no cash component would stay outside the tax under article 150 VH bis.
An exit tax for crypto
Amendment I-CF1822, adopted Oct. 8, would extend the exit tax to crypto-assets through article 167 bis of the tax code. It is built on the existing rules for stocks: the same €800,000 threshold, similar residency conditions, and payment deferral and remission mechanisms modeled on the securities regime, including relief if the taxpayer returns.
Descriptions of the measure differ on whether the €800,000 is measured against a household's total crypto holdings or its unrealized gains. The adopted text and any floor changes will settle that.
The mechanism is the same as in the securities regime. Changing tax residence is itself the taxable event, and the bill is calculated as if the portfolio had been sold on the day of departure. A holder can owe tax on gains never realized in cash. The deferral provisions are what would keep that from forcing a sale.
The loss-relief sweetener
The package is not all new burden. Amendment I-CF798, from deputy Daniel Labaronne and adopted Oct. 7, would let investors carry realized crypto losses forward for up to 10 years. Under current rules, losses beyond a year's taxable gains cannot be carried to later years. The change would mirror how losses on traditional securities are treated.
Sponsors say the overall aim is to bring crypto taxation closer to the treatment of conventional financial assets.
Where it stands
Crypto Briefing reports that the budget's revenue section was rejected on Oct. 9, which means the amendments are not carried forward automatically and must be reintroduced on the Assembly floor. It also reports a vote scheduled for Oct. 20. Deputies will have to defend each measure again in public session.
The EU's DAC8 reporting framework has applied since Jan. 1, 2026. It requires platforms to collect client identity and transaction data and pass it to tax authorities, with the first cross-border exchanges between states due in autumn 2027. Reporting under DAC8 does not itself make any transfer taxable.
France's implementation of DAC8 has already drawn a legal challenge from the companies Bull Bitcoin and Paymium. The Council of State rejected their request for an emergency suspension.
Greece is also moving on crypto. Its draft proposal would tax individual crypto gains at 10% with a €500 annual exemption, but only on conversions to fiat. Crypto-to-crypto exchanges would be exempt. That is narrower than the French stablecoin amendment, which reaches conversions that never touch a bank account.
The budget backdrop
France's finances are under pressure. Bank of France Governor Emmanuel Moulin told the Senate on Sept. 25 that the country must do "everything possible to avoid a sovereign debt crisis" ahead of the 2027 presidential elections. He added that it would be "misguided to expect the European Central Bank to ride to the rescue."
France's 10-year borrowing costs have reached 4.7%, the highest since the 2008 financial crisis. Public debt is projected at 119.3% of GDP this year and 121.7% in 2027. Debt interest alone is expected to reach €65 billion.
No source ties the crypto amendments to those numbers. The sponsors' own stated rationale is closing a loophole and aligning crypto with stocks.
What comes next
The amendments return to the Assembly floor when budget debate opens on Oct. 13. If they are reintroduced and adopted, the stablecoin tax, the exit tax and the 10-year loss carryforward would all take effect on Jan. 1, 2027. The Assembly's scheduled vote on Oct. 20 will show whether any of the three survives.
Sources used for this briefing
This briefing was written by UBH's AI agent — these are the reporting inputs it draws on, linked so you can verify.


