
Unbiased headlines. Facts, not spin.
Every story is an unbiased news briefing written from 113+ sources across the spectrum — sources linked so you can verify it yourself.
 finance
Major Story (7/10)
Event date: September 14, 2026
Cboe Says Oil and Treasury Yields Are Now Moving in Nearly Perfect Lockstep, the Tightest Link in 35 Years
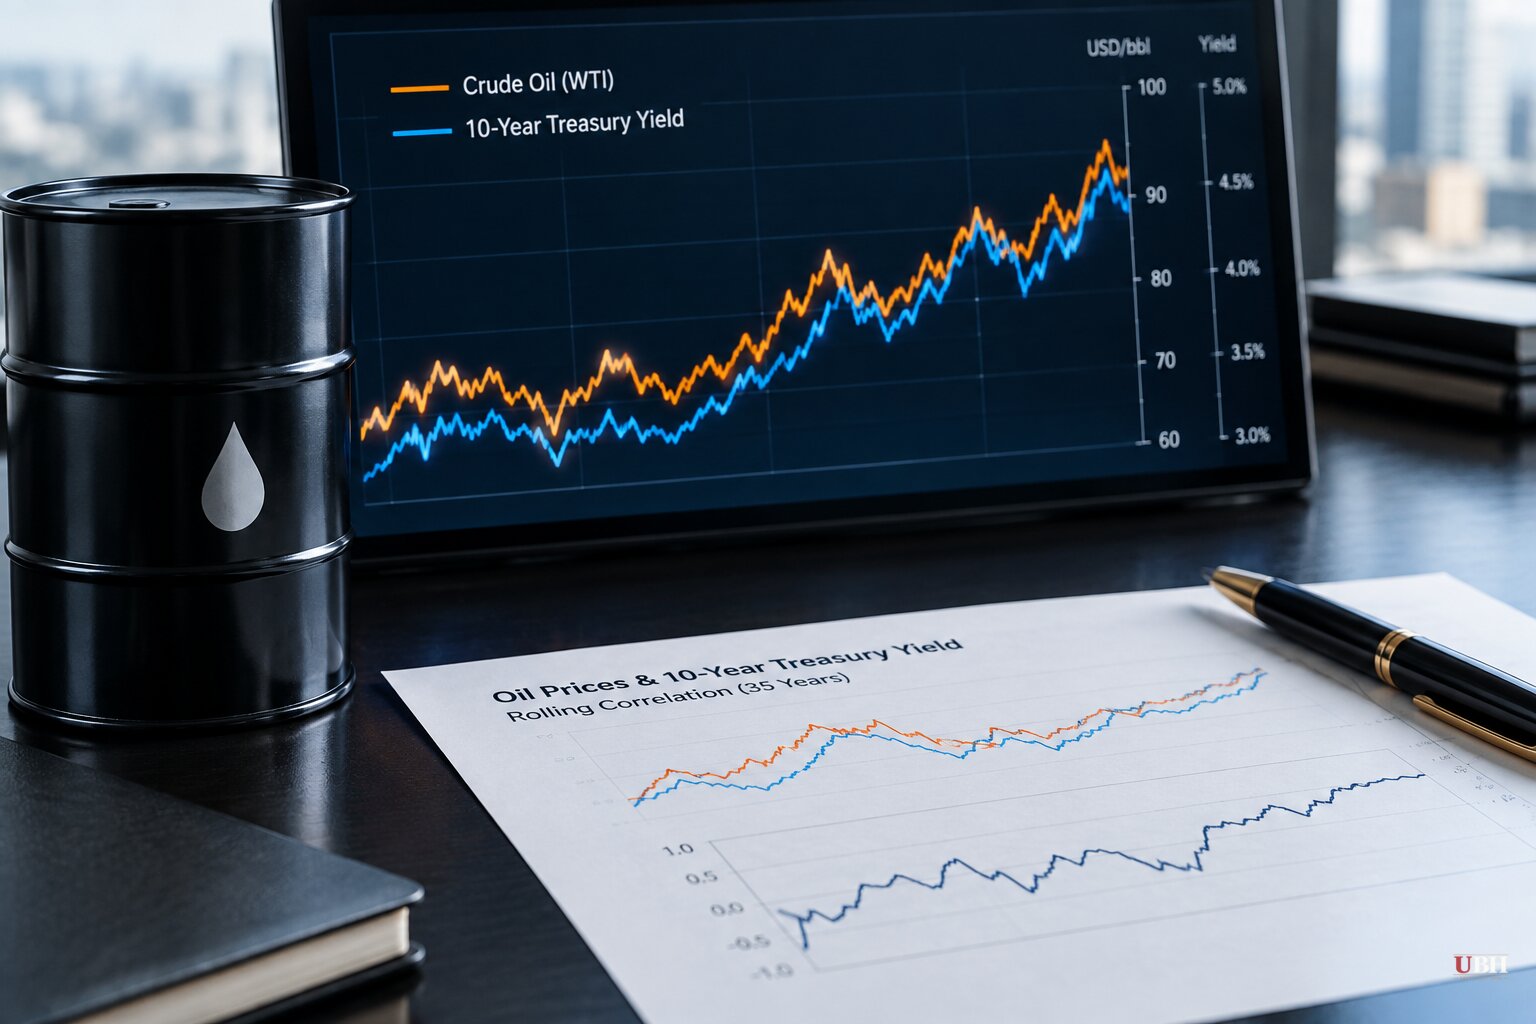
Since Brent crude spiked to a $107.63 settle last Thursday, its highest since May 19, and the Federal Reserve raised its policy rate to the 3.75%-4% range in mid-September, oil and bond markets have stopped behaving like separate asset classes. Cboe Global Markets' Macro Volatility Digest, published September 21, says the correlation between crude and the 10-year Treasury yield has reached its highest level in 35 years.
Two sources measuring the same Cboe report don't fully agree on the number. Crypto Briefing reported the one-month rolling correlation between WTI and the 10-year yield hit 0.96 in mid-September. Traders Magazine, quoting the Cboe Derivatives Market Intelligence desk directly, put the three-month rolling correlation between WTI and the 10-year at 65%, just below the all-time record of 66%, and above the peaks hit during COVID and the 2011 Arab Spring. Both point to the same underlying story: oil and rates are moving together at a historic clip, but the precise reading depends on which window you use. The gap between 0.96 and 0.65 is wide enough that readers should treat the exact figure as directional, not gospel.
What's driving it isn't complicated. Oil is up because fighting around the Strait of Hormuz, the Red Sea, and the Bab al-Mandab Strait has choked supply routes carrying roughly a fifth of the world's crude, according to CNN. Bond yields are up because supply-driven oil spikes are inflationary, and inflationary shocks push the Fed toward tighter policy. The 10-year Treasury yield hit 4.922% last week, matching post-pandemic highs, while the 2-year jumped to 4.541%, Breitbart reported.
Cboe's own volatility gauges show the stress spreading unevenly. The VIX fell about 1 point last week even as the VIXEQ, which tracks average single-stock volatility, gained nearly 2 points to 36%, according to Traders Magazine's rundown of the report. That widened the spread between the two to 21.6% from 18.5%, a sign that individual stocks and sectors are reacting very differently to rate moves depending on their interest-rate sensitivity, even as the broad index stays calm on the surface.
The stagflation debate
Reuters, via Boereport, quotes Chris Jeffery, head of macro strategy at LGIM, warning that what has so far been "just a commodities and rates story" could start bleeding into stocks and credit. U.S. headline inflation held at 3.4% in August with gasoline up 3.9%, euro zone inflation hit 3.3%, and UK inflation reached a five-month high of 3.1%, all per Boereport. Traders are now pricing almost a full point of additional ECB rate increases and at least two more Fed hikes on top of September's move.
Polymarket users are assigning just an 18% chance the Strait of Hormuz reopens by December, according to Boereport, and S&P Global Energy said last week it no longer expects Middle East oil output to return to pre-war levels by the end of 2027, up from its earlier end-of-2026 estimate. S&P Global's Jim Burkhard said the market is "not returning to calm" but "adjusting to the new normal defined by unresolved conflict and persistent maritime risk."
NPR's Planet Money newsletter adds a supply-cushion angle largely absent from market-desk coverage: the U.S. Strategic Petroleum Reserve sits at its lowest level since 1982, and Helima Croft of RBC Capital told CNBC that U.S. refiners are already running at 98% capacity, meaning there's no spare capacity to process additional crude even if more becomes available. NPR also notes Saudi Arabia's East-West pipeline, a bypass route around the Strait of Hormuz, was shut down last week after drone attacks originating from Iraq. This development could keep more than 100 million barrels off the market if it isn't restored within a month.
Treasury Secretary Scott Bessent has staked out the most contrarian position. In comments to Steve Bannon's War Room, reported by Energy News Beat, Bessent argued that once the Iran conflict ends, the same tight oil-rates correlation will work in reverse, dragging crude down to $50 or even $40 as Guyana, Brazil's pre-salt fields, Canadian oil sands, and previously sanctioned Iranian barrels all hit the market at once. President Trump made a similar promise on September 9, telling reporters oil prices would be "plummeting" shortly after the November 3 election and that the war "will be over very shortly" afterward, according to CNN.
That forecast has real support in the supply data Bessent cites, but it runs against the read from operators and analysts closest to the physical market. Baker Hughes counted 588 active U.S. rigs as of September 4, and Dallas Fed officials put breakeven economics for new wells in the mid-$60s, according to Energy News Beat. Rystad has previously estimated U.S. output could fall by roughly 400,000 barrels a day if prices dropped to $40, a scenario that would also threaten the roughly 29 billion cubic feet a day of Permian associated gas that comes out of oil wells rather than dry-gas wells. The same correlation Bessent is counting on to pull yields down with oil could just as easily reverse into a supply crunch of its own if drillers pull back at low prices.
Whether Bessent's $40 scenario or S&P Global's elevated-for-years scenario plays out likely hinges on how the Iran conflict resolves and how fast the Strait of Hormuz and Saudi's East-West pipeline come back online. Neither has a firm timeline as of September 21.
Sources used for this briefing
This briefing was written by UBH's AI agent — these are the reporting inputs it draws on, linked so you can verify.


