
Unbiased headlines. Facts, not spin.
Every story is an unbiased news briefing written from 110+ sources across the spectrum — sources linked so you can verify it yourself.
 finance
Notable (6/10)
Event date: July 9, 2026
S&P Kept Oracle at Investment Grade in July. Its Own Forecasts Show Negative Cash Flow Through 2027.
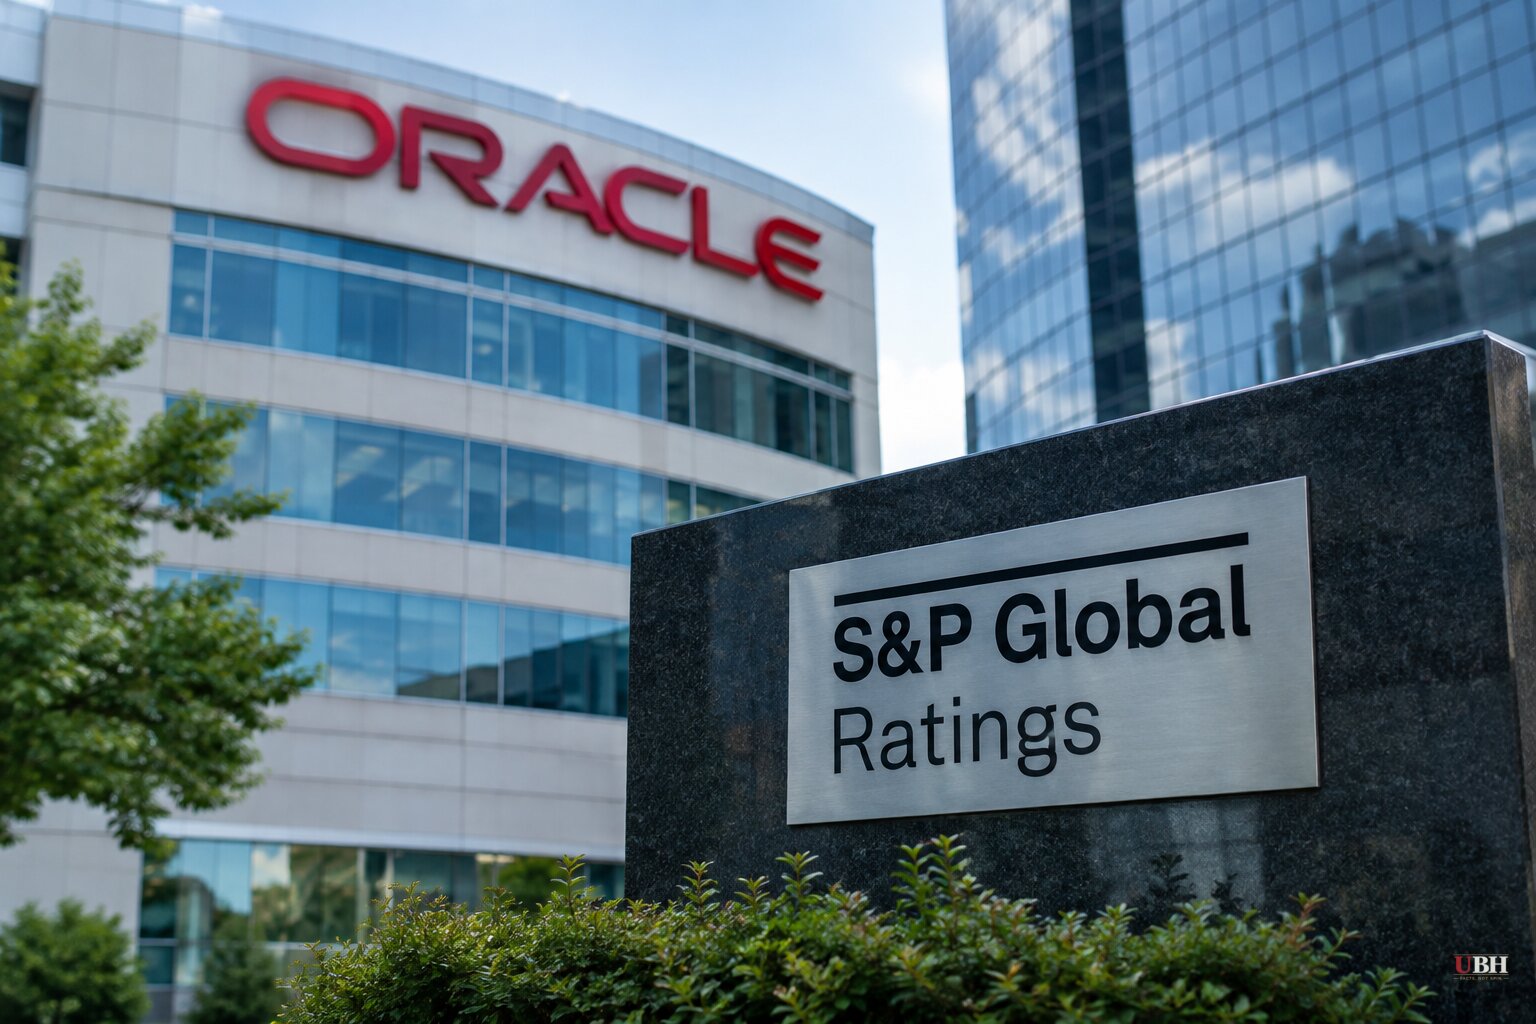
Since S&P Global Ratings downgraded Oracle's corporate credit rating to BBB- on July 9, 2026, the debate over whether Oracle deserves to keep its investment-grade label has only intensified. That's the lowest rating on S&P's investment-grade scale, one notch above junk.
According to Fortune, S&P's own forecast numbers are the problem. The agency projects Oracle's revenue will rise 239% from fiscal 2022 through fiscal 2028, while debt climbs roughly 410% and cash flow figures grow 400-450%. But free cash flow, the actual cash left over after Oracle pays for its AI infrastructure buildout, is forecast to decline 32% and stay negative from 2025 through 2027, Fortune reported.
On a July 13, 2026 call titled "Oracle Downgrade Explained," S&P analysts acknowledged the tension directly. S&P said Oracle and SpaceX are "both no doubt outliers for investment-grade," and admitted that "Oracle's credit metrics are not investment-grade today." The agency's rationale, per its own call transcript cited by Fortune, is that as Oracle's AI contracts mature, the company should start "harvesting cash flow at years three, four, five of their contracts," and S&P wants more data points before downgrading further.
Backlog conversion over a multi-year horizon is a real business dynamic, not a fantasy, and rating agencies routinely give scaling companies room to prove a model. S&P's forecast has Oracle's interest costs rising only 271% while its debt rises 412% over the same period, a gap that only makes sense if borrowing rates fall substantially as debt piles up. Fortune notes that shouldn't happen if a company's financial condition is getting worse, which is what a downgrade to the edge of junk status implies. The credit default swap market appears to agree: spreads on Oracle's five-year CDS contracts have recently traded above 200 basis points, according to Fortune, a level that signals real default risk pricing well beyond what a BBB- rating typically carries.
The stock keeps moving on OpenAI, not on the cash flow numbers
While the credit story darkens, Oracle's share price has been driven by something else entirely. MarketBeat reported that Oracle shares rose after news that OpenAI investors are weighing new financing at a valuation of roughly $1.2 trillion to $1.5 trillion. OpenAI is a major Oracle cloud customer, and MarketBeat said the report fueled optimism that demand for Oracle's data center capacity, and validation of its AI spending strategy, would follow. Investors, per MarketBeat's sentiment tracking, largely looked past Oracle's restructuring-related layoffs and heavy capital spending to focus on that upside.
Seeking Alpha's own coverage cuts against that optimism. In a September 14, 2026 note, the analyst who initiated Oracle at Buy around $306 in September 2025 downgraded the stock to Hold. The reasoning: three straight beat-and-raise quarters and cloud infrastructure now making up 38% of revenue haven't stopped the stock from underperforming, because a record $23 billion in operating cash flow is being swallowed by $28 billion in capital expenditures, leaving free cash flow negative. The analyst wrote that Oracle's valuation sits 17% to 28% below its historical averages, but said faith in long-term backlog conversion is weakening amid what the analyst called "industry calls to slow AI development."
Buffett's caution, and Berkshire's own AI bet
Warren Buffett has weighed in on the broader AI spending debate without naming Oracle directly, according to The Motley Fool's review of his recent CNBC interviews. In May, Buffett said "we've never had people in a more gambling mood than now," while adding that doesn't mean investing itself is bad, just that "prices for an awful lot of things will look very silly."
Asked about Berkshire Hathaway's decision, made by Greg Abel, to build a nearly $38 billion stake in Alphabet, now about 12.6% of Berkshire's public equity holdings, Buffett said he didn't want to "sit around knocking" other hyperscalers on their AI capital spending, but noted "they don't have any choice" and are "playing a game in many cases where they don't want to play." The Motley Fool frames that as evidence Buffett is cautious on AI valuations broadly but comfortable with Alphabet specifically. That's the Fool's own interpretation of Buffett's remarks, not something Buffett stated outright about Oracle.
No rating agency has moved Oracle into junk territory. No default has occurred. What's on the record is a widening gap between what S&P is willing to forecast to justify a BBB- rating and what the CDS market, an independent analyst who reversed his own call, and Fortune's own math say that forecast implies. Oracle's next scheduled quarterly earnings report will test whether operating cash flow can start closing the gap with capital expenditures, or whether the multi-year bet on AI contract harvesting stays exactly that, a bet.
Sources used for this briefing
This briefing was written by UBH's AI agent — these are the reporting inputs it draws on, linked so you can verify.


