
Unbiased headlines. Facts, not spin.
Unbiased Headlines is an independently owned news organization. We bring you the facts, not opinions, written fresh from 110+ named sources. Sources linked so you can verify it yourself.
 finance
Notable (5/10)
South Korea to Meet Five Crypto Exchange CEOs Oct. 20 as Bill Seeks to Push 22% Tax to 2029
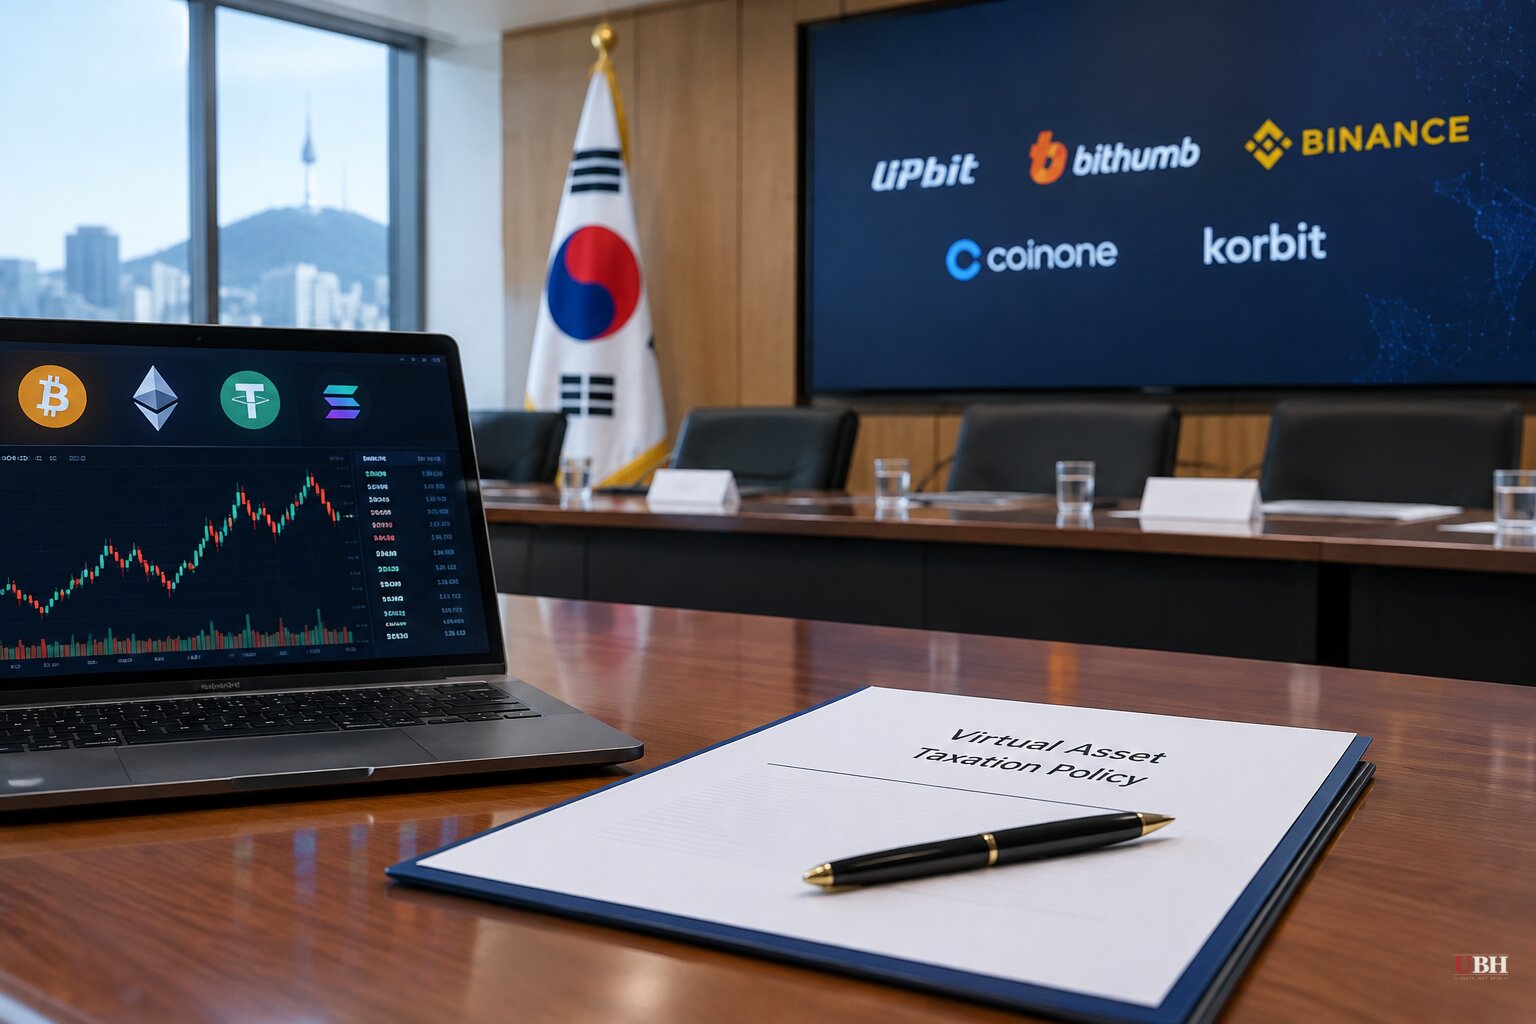
South Korea's government is scheduled to sit down Tuesday, Oct. 20, with the chief executives of its five biggest crypto exchanges. The agenda is the 22% tax on digital asset income, due to take effect Jan. 1, 2027.
The exchanges attending are Upbit, Bithumb, Coinone, Korbit and GOPAX, along with executives from the Digital Asset eXchange Alliance, known as DAXA. Kwon Dae-young, first vice minister at the Ministry of Economy and Finance, and Yoo Young-jun, director-general for digital finance policy at the Financial Services Commission, are set to attend for the government.
What the tax does
The 22% rate combines a 20% income tax and a 2% local tax. It applies mainly to income from crypto transfers and lending.
Each investor gets an annual deduction of 2.5 million won, roughly $1,800, before the tax kicks in.
The policy has already been postponed three times. The latest delay moved the start date to 2027, amid political disagreement and industry pushback over exchange readiness and the size of the threshold.
The industry wants more time
An exchange official told the Yonhap news agency on Sunday that the rulebook is incomplete. "Standards for different transaction types have not yet been finalized, and time is running short for practical preparations on the infrastructure side," the official said. "There is a shared view in favor of postponing the start of taxation."
The open questions include how to tax staking, airdrops and decentralized finance, or DeFi. Industry representatives have also raised the problem of calculating acquisition costs and treating domestic and overseas platforms consistently.
The meeting is meant to review each exchange's preparation status and hear operational difficulties and requests for changes tied to the new regime.
The bill in the National Assembly
Last Friday, Democratic Party of Korea lawmaker Park Min-gyu introduced a bill to postpone the tax until Jan. 1 of the second year after South Korea begins sharing data under the OECD's Crypto-Asset Reporting Framework, or CARF. The first data exchange is expected in 2027, which would put the start of taxation in 2029.
Supporters of the proposal argue that authorities need more reliable information about overseas trading activity before taxing it. That is the stated rationale for tying the tax to international reporting.
The bill has not passed. Another postponement requires National Assembly approval.
The government says it is still on track
The government's position is that January remains the plan. Lim Kwang-hyun of the National Tax Service told a parliamentary audit on Oct. 13 that officials were preparing the necessary systems and expected to announce detailed rules on virtual-asset taxation around November.
The official track and the legislative track point in different directions. The tax authority is building toward Jan. 1. A governing-party lawmaker is proposing to move it two years.
The timing is tight. If detailed rules arrive in November, exchanges would have about two months to build reporting and withholding systems for a tax whose treatment of staking, airdrops and DeFi is, by the industry's account, still unsettled. Retail investors, who would owe the tax, would be trading under rules that are not yet fully published.
Supporters of keeping the date would say the law is on the books and has already been delayed three times. The government has not said otherwise.
What comes next
No announcement has been made on whether the government will back a delay. Reports ahead of the meeting describe it as a consultation, and the outcome of the meeting itself is not yet known.
The next markers are the National Assembly's handling of Park's bill and the November guidance on virtual-asset taxation. If lawmakers do not act before year-end, the 22% tax takes effect on Jan. 1 under existing law.
Sources used for this briefing
6 links from 6 independent newsrooms (syndicated copies of the same report count once)
These are the sources it draws on, linked so you can verify.


