
Unbiased headlines. Facts, not spin.
Unbiased Headlines is an independently owned news organization. We bring you the facts, not opinions, written fresh from 110+ named sources. Sources linked so you can verify it yourself.
 finance
Major Story (7/10)
Nasdaq Futures Rise Before Monday Open After 4.48% Weekly Drop in the Index
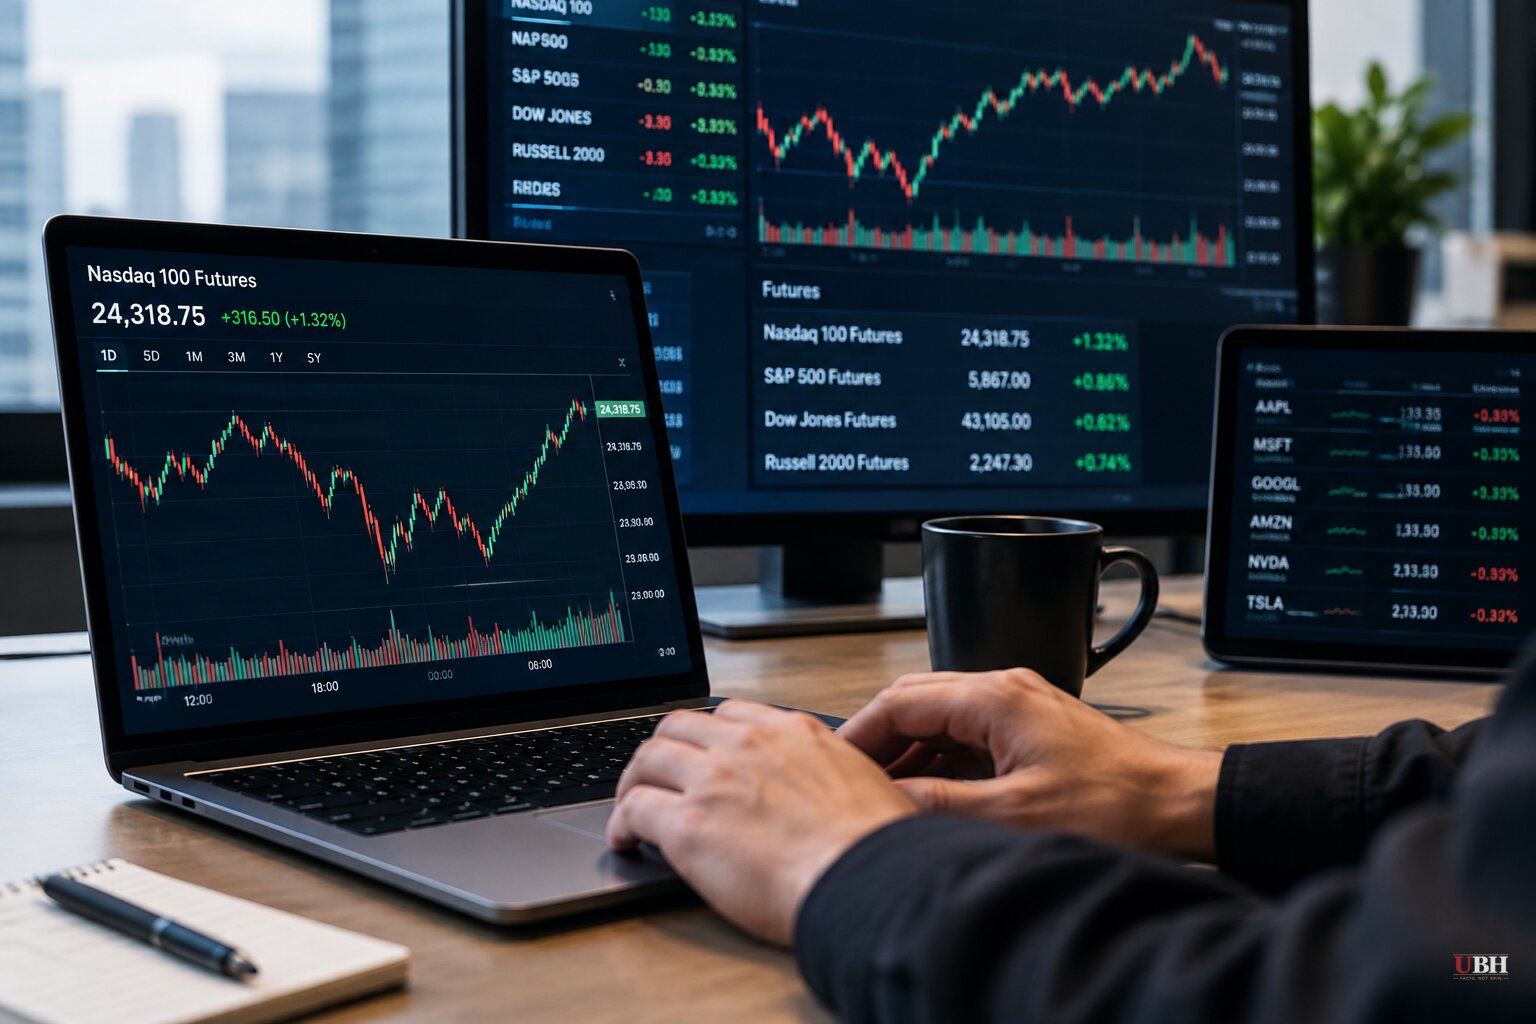
Since Friday's close on Oct. 16 left the Nasdaq Composite down 4.48% for the week, U.S. stock futures have turned higher. As of this pre-market hour on Monday, Oct. 19, regular trading has not started. Everything below about U.S. stocks today is an indication, not an opening price.
Nasdaq-100 futures were up 1.32% in the latest overnight reading, up from a 0.4% gain when contracts reopened Sunday evening. Dow futures were ahead 0.53%, or 278 points. S&P 500 futures gained 0.8% as of 11:30 p.m. ET Sunday.
What Friday left behind
The Nasdaq Composite closed Friday at 26,140.03 after dropping 2.14% on the day. It snapped a four-week winning streak. The S&P 500 finished at 7,659.44, down 1.95% for the week, its worst since late June. The Dow closed at 52,002.41, up 0.67% for a second straight weekly gain. The Russell 2000 fell 3.05%.
AI infrastructure names took the worst of it. CoreWeave fell 13.65% Friday and 25.21% for the week. Nebius Group dropped 12.18% Friday and 25.15% for the week. Palantir fell 7.22% Friday.
Two explanations for the rout
The sell-off has two causes on offer. CNBC reported, citing sources, that Anthropic's third-quarter revenue totaled $16.8 billion, up from $11.6 billion in the second quarter. The figure raised questions among investors about the pace of growth relative to the AI build-out. Anthropic has not confirmed the number in the material we have seen.
The other is inflation. Hotter-than-expected CPI data pushed Treasury yields up. The 10-year climbed above 5.30% on Wednesday before easing toward 5.20%. It then fell nearly 13 basis points to 5.05% on Thursday as investors sought government bonds. The 30-year edged down to 5.43%.
Skyler Weinand, chief investment officer at Dallas-based Regan Capital, told The Epoch Times the inflation uptick "is likely to lead the Federal Reserve to start a rate-hiking cycle." He expects a pause in October, then hikes starting in December and running through June 2027.
Credit is where the stress shows
CoreWeave uses heavy debt to build data centers it rents to tech companies. Its credit default swaps have reached distress levels, and corporate bond investors have started to shun the company. Its 25% weekly drop was its largest since November 2025.
Goldman Sachs traders wrote Friday that "AI Credit Spreads and hyperscalers specifically are at the widest levels of the year. The last time spreads were nearly this high, the underlying equities were 15% lower." They added that "AI Capex has likely peaked and financing, sustainability, and returns on capital have become the debate." They also noted Friday saw the second-highest volume of puts traded, behind only June.
The case for a rebound is the one traders are acting on: that the dip is a buying chance ahead of earnings. The weekend's futures gains reflect that, and CNBC noted optimism that this week's results will stabilize the market. Goldman's own desk described market breadth as low and pessimism as rising.
Earnings week
The schedule, with consensus estimates cited by Stocktwits data:
- Netflix, Tuesday after the close: estimated EPS of $0.82 on $12.87 billion in revenue, versus $0.59 a year earlier.
- SpaceX, Tuesday evening: its second quarterly update as a public company, with estimated EPS of $0.14 on $12.8 billion.
- Tesla, Wednesday after the close: estimated EPS of $0.45 on $27.94 billion, versus $0.50 and $28.09 billion a year earlier.
- Meta, Wednesday after the close: estimated EPS of $6.58 on $63.34 billion.
General Motors, Procter & Gamble, American Express, Lam Research and Texas Instruments also report this week. These are estimates. None of the results are out.
Oil and overseas markets
Brent crude futures fell nearly 1.9% overnight to $107.88 a barrel. West Texas Intermediate slipped 0.8% to $100.58. Earlier Sunday, Brent had been at $108.80 and WTI at $101.18.
Prices had briefly spiked after Ukraine launched a wave of drone strikes on Sunday that started fires at an oil terminal and depot in St. Petersburg, according to Gov. Alexander Beglov. Attacks on tankers in the Persian Gulf have also picked up. Longer-dated oil futures have been climbing on expectations that energy-infrastructure disruptions could last well into 2027.
Asia was mostly lower on Monday. Japan's Nikkei 225 lost 1.65% and the Topix fell 1.12%. South Korea's Kospi dropped 1.29% and the Kosdaq slipped 0.93%. China's CSI 300 slid 0.28%. Australia's S&P/ASX 200 rose 0.37%.
The Wall Street Journal reported, citing people familiar with the matter, that Russian President Vladimir Putin has proposed a three-way summit with President Trump and Chinese President Xi Jinping. Trump has not responded directly to that report.
Monday is also the 39th anniversary of the 1987 crash. Futures suggest no repeat so far. The first real test comes when the Nasdaq opens at 9:30 a.m. ET, followed by Netflix and SpaceX on Tuesday evening and Tesla and Meta on Wednesday.
Sources used for this briefing
7 links from 5 independent newsrooms (syndicated copies of the same report count once)
These are the sources it draws on, linked so you can verify.


