
Unbiased headlines. Facts, not spin.
Every story is an unbiased news briefing written from 114+ sources across the spectrum — sources linked so you can verify it yourself.
 finance
Major Story (7/10)
October 6, 2026 at 08:33 PM
JPMorgan: Deeply Distressed Leveraged Loans Hit $65 Billion, Worst Since Pandemic, as NY Fed Quietly Reviews Bank Exposure to Private Credit
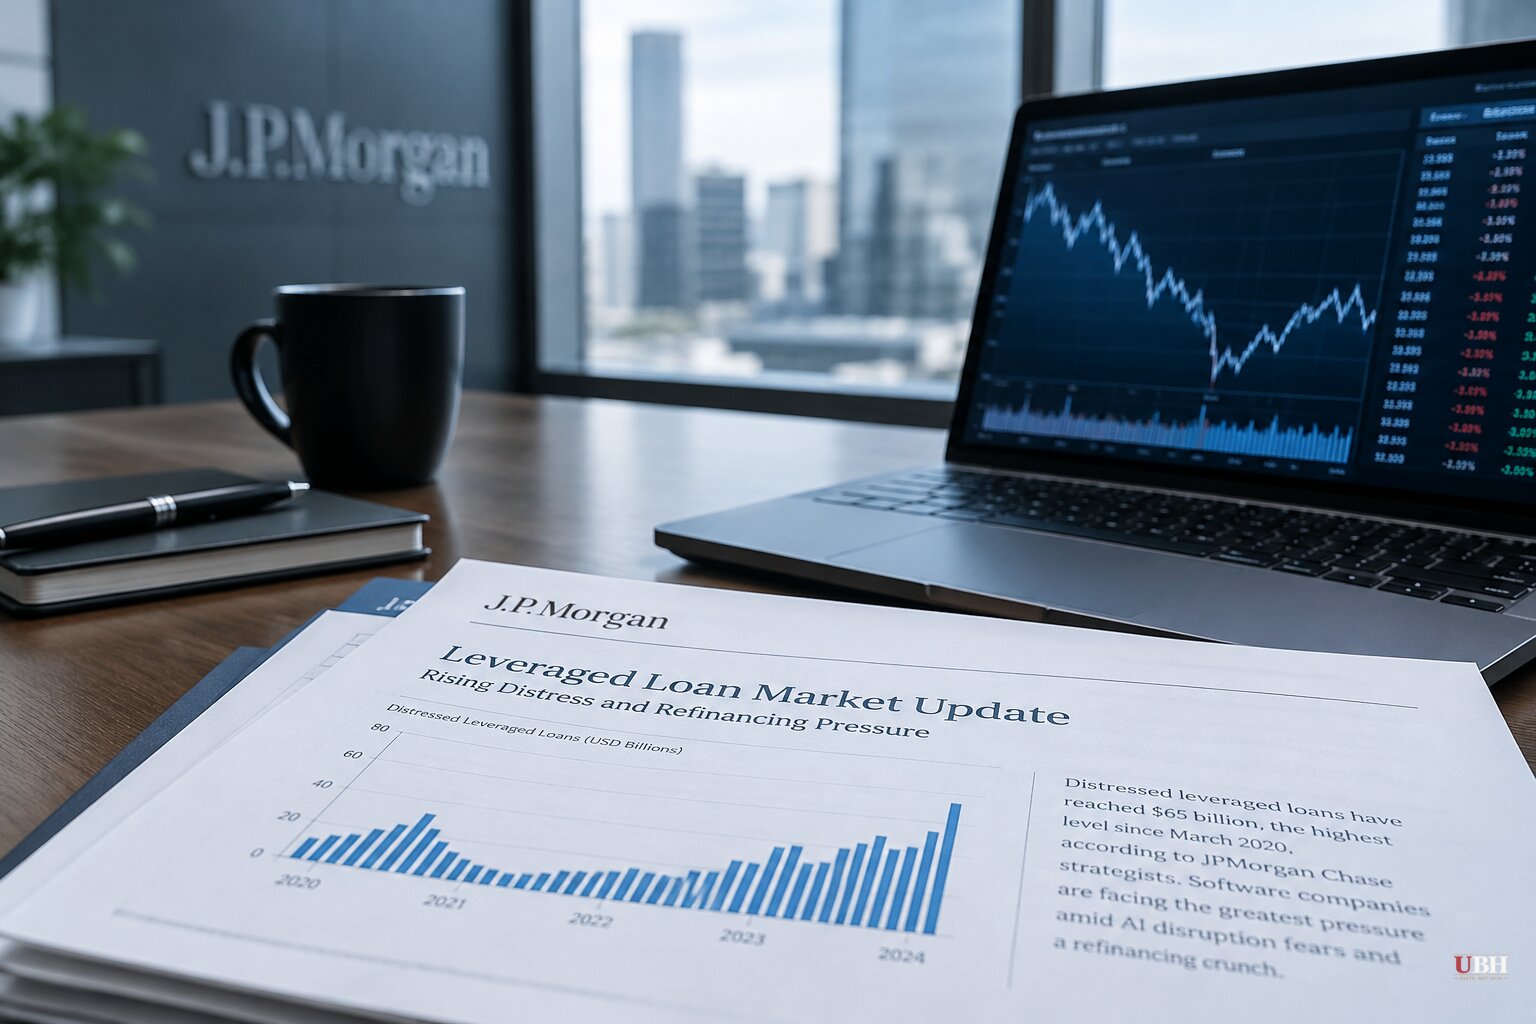
Since Bill Gross told investors Monday, October 5, to dump bonds as US credit hit $84 trillion, and distressed corporate bonds climbed to levels unseen since the 2023 banking crisis, the pressure has now shown up squarely in the leveraged loan market.
JPMorgan Chase strategists, including Nelson Jantzen, wrote Tuesday, October 6, that loans trading below 60 cents on the dollar, the deeply distressed bucket, rose to $65 billion, up from $40 billion a year ago. That is the highest level since March 2020, according to the JPMorgan note cited by Bloomberg.
The broader distressed category, loans trading at or below 80 cents, hit $139.8 billion, a nearly 90% jump from a year earlier and just $4 billion shy of the peak recorded in May 2020, according to Quartz's reporting on the same JPMorgan data. The number of issuers below that 80-cent threshold has climbed to roughly 141, up 35 from last year.
Software Is Carrying the Load
Technology accounts for 39% of all distressed loan volume, or $54.4 billion, more than any other sector, according to the JPMorgan report. Software names CDK Global, QLIK Technologies and Quest Software are among the biggest contributors, Quartz reported.
Two things are converging on these borrowers. First, more than $100 billion in software debt is coming due, and refinancing it on workable terms is getting harder. Second, investors are betting that AI tools could gut the business models behind some of these companies, making their future cash flows less reliable.
That second worry has teeth because of a timing gap. Loans originated before 2024 largely did not price in AI as a business risk at all, according to Quartz, which cited institutional investors and credit analysts flagging this as a source of underpriced exposure sitting on direct lending books right now.
Low Default Rate, High Skepticism
Actual payment defaults remain rare. The trailing 12-month default rate for the leveraged loan index sat at 0.93% in July 2026, according to Crypto Briefing's review of the JPMorgan data. JPMorgan projects that rate climbing to 4.50% next year, with high-yield bond defaults rising from 2.25% to 2.75%, according to Quartz.
The gap between distressed pricing and formal defaults is partly explained by liability management exercises and distressed exchanges, tools that let companies swap troubled debt for new terms without filing bankruptcy. Credit analysts who track this consider it a way defaults get masked rather than resolved, though that interpretation is a judgment call, not a settled fact, and JPMorgan's own data shows CCC-rated loans down 1.97% this year while every higher-rated tier posted gains. CCC high-yield spreads have topped 1,000 basis points, the highest since the 2023 regional banking crisis, with yields at 15.58%, the highest since November 2022, Quartz reported.
The Market Is Also Still Lending Hard
While software credits rot, the primary market had one of its biggest weeks of the year. Paramount finalized its $57 billion-equivalent leveraged buyout financing for the Warner Bros. Discovery acquisition, including $12.4 billion in second-lien notes and $9.45 billion in loans, according to Octus. A leveraged finance banker described order books as "staggeringly strong," with roughly $70 billion in loan issuance in September alone.
JPMorgan is separately marketing a $5 billion loan for Volta Infrastructure Holdings, an AI cloud buildout tied to roughly 36,000 Nvidia GPUs and a Norwegian data center lease with Bitdeer, at a discounted price and a spread of 6.25 to 6.50 percentage points over the benchmark, working out to roughly 11% all-in yield, according to Briefs. Commitments on that unrated deal are due October 14.
The split is stark. Banks are happy to underwrite new AI infrastructure debt at double-digit yields while the AI disruption narrative is simultaneously crushing the loans of older software companies.
What Regulators Are Actually Doing
The New York Fed has been visiting JPMorgan, Wells Fargo, Barclays and Morgan Stanley since spring to review their lending to private credit firms and understand overall exposure and risk, according to Newsquawk. No investigation has been announced, no findings have been published, and no enforcement action has been disclosed. This appears to be routine supervisory fact-finding, not a formal probe, and nothing in the available reporting suggests otherwise.
The strongest case for concern is straightforward: banks lend to private credit funds, private credit funds lend to exactly the kind of leveraged software borrowers now trading at 60 cents on the dollar, and nobody outside the Fed currently knows how large or concentrated that chain of exposure is. The strongest case against alarm is equally straightforward: default rates remain under 1%, stronger credits are trading near par, and Paramount just placed $57 billion in debt without apparent trouble finding buyers.
Both things are true at once. Whether the NY Fed's bank-by-bank review turns into a public report, a capital rule, or nothing at all is an open question nobody has answered yet. Volta's October 14 commitment deadline will be an early test of whether lenders still want AI infrastructure exposure at 11%, even as software credit built on the same AI story keeps sliding.
Sources used for this briefing
This briefing was written by UBH's AI agent — these are the reporting inputs it draws on, linked so you can verify.


