
Unbiased headlines. Facts, not spin.
Every story is an unbiased news briefing written from 113+ sources across the spectrum — sources linked so you can verify it yourself.
 economy
Notable (6/10)
October 5, 2026 at 08:11 PM
ISM Services Index Slows to 54.9 in September as Price Gauge Hits Four-Year High, While a Rival Survey Shows the Opposite
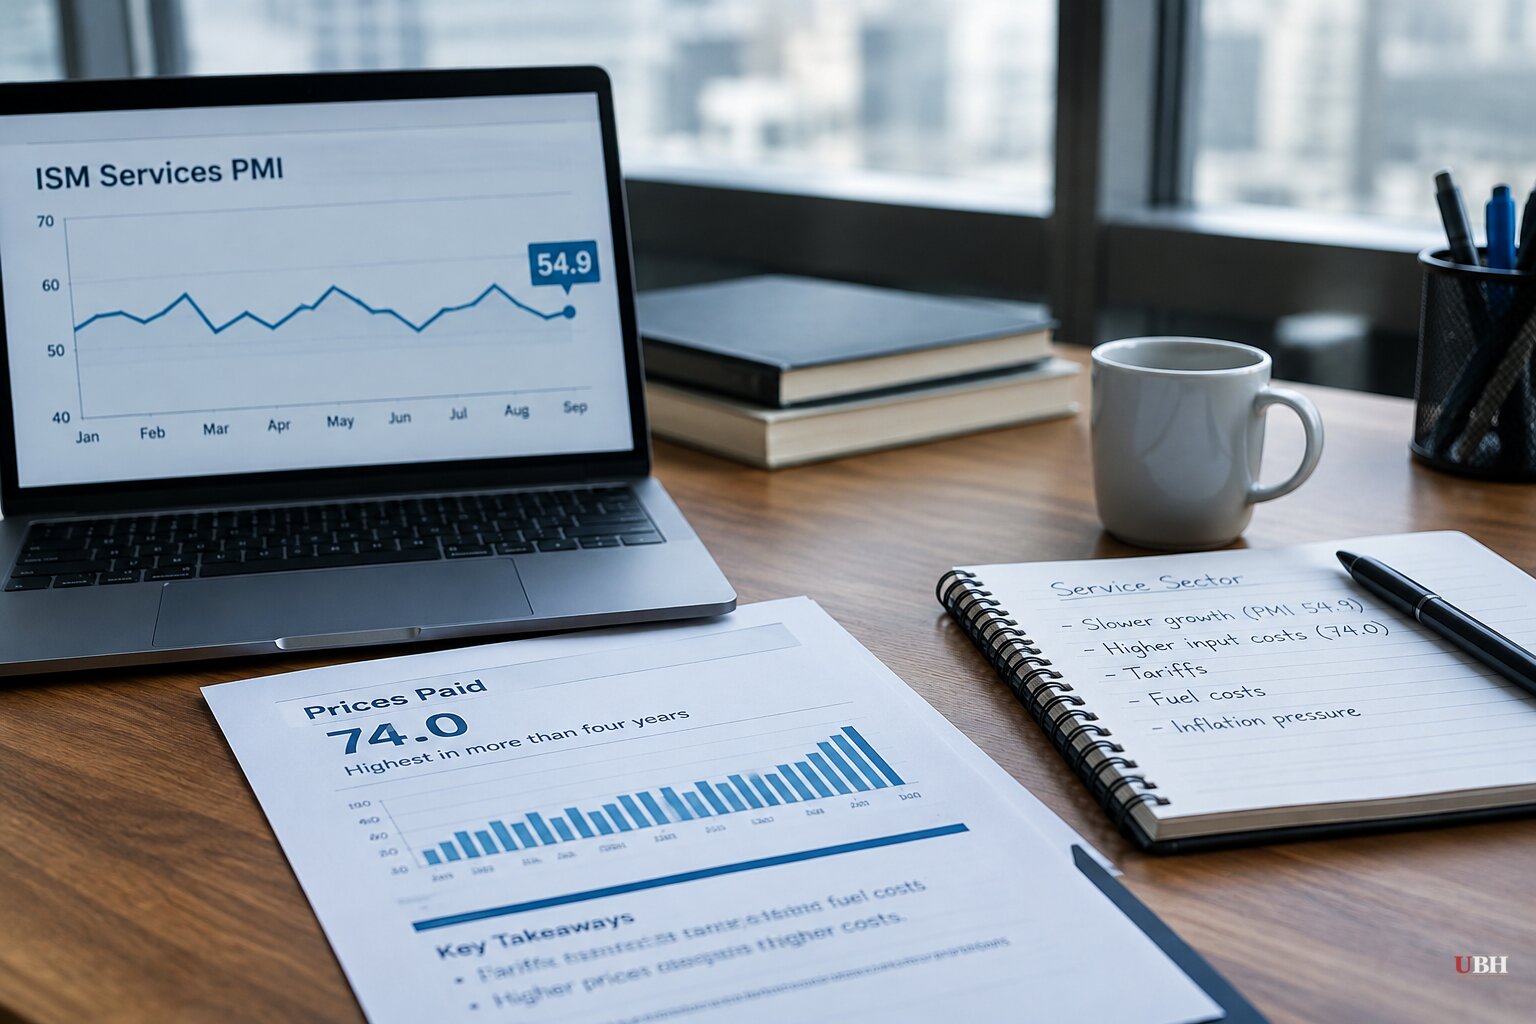
The Institute for Supply Management said Monday its services sector purchasing managers index fell to 54.9 in September from 55.4 in August, missing the 55.2 reading economists polled by Reuters had expected. Anything above 50 signals expansion, and the services sector, which makes up more than two-thirds of U.S. economic output, has now stayed in growth territory for 27 straight months, according to BigGo Finance.
The headline number wasn't the real story. The ISM's prices-paid index jumped to 74.0 from 72.6, according to Traders Union, the highest reading in more than four years, Reuters reported. Steve Miller, who chairs the ISM Services Business Survey Committee, said "tariffs and fuel cost impacts were the most cited issues impacting respondents' supply chain," adding that fuel costs "were mentioned twice as often as any other single issue impacting performance."
Why Fuel Costs Are Spiking
Reuters, in reporting by Lucia Mutikani, tied the fuel-cost surge to the U.S.-Israeli war with Iran, which it said has disrupted commodity flows through the Strait of Hormuz and pushed diesel prices to record highs, hitting farmers and truckers directly.
The rest of the ISM report showed a sector under strain from strong demand it can barely keep up with. New orders eased to 59.8 from 60.9. Export orders fell 9.4 points to 46.9, landing in contraction for the first time in eight months. Business activity cooled to 56.5 from 61.7. Supplier deliveries slowed for a 22nd consecutive month, hitting 53.2, which keeps feeding the input-cost problem. Employment, at least, swung back to growth at 50.1 from 47.8 in August. Thirteen of seventeen services industries reported growth, Reuters said, while mining and construction were among four that contracted.
The Fed's Dilemma
Matthew Martin, senior U.S. economist at Oxford Economics, told Reuters "the prices index continues to trend markedly higher, and the uptick in supply chain stress and backlog of new orders suggest price pressures are building," arguing the underlying economy is strong enough to "withstand additional policy tightening." Some analysts, Reuters reported, think that argues for the Federal Reserve to raise rates again this month and in December.
But that's not where the smart money sits. Cooler-than-expected inflation readings in July and August, combined with a sharp slowdown in September nonfarm payroll growth, have reduced the odds of a hike at the Fed's October 27-28 meeting, according to Reuters. Economists instead are leaning toward December for the next move. A real tension exists here: weak jobs data argues for patience, hot services prices argue for action, and the Fed has to pick one.
If the Fed holds in October because the labor market looks soft, and prices keep climbing the way September's ISM data suggests, policymakers risk falling behind the inflation curve again. It's the exact setup critics of 2021-era Fed messaging warned about. The counter-argument, per Martin, is that strong underlying growth gives the Fed room to wait.
A Different Picture From S&P Global
While the ISM was reporting a cooling sector, Breitbart covered a separate survey from S&P Global showing services activity hit a five-year high in September. The S&P Global Services PMI Business Activity Index rose to 58.8 from 56.5, its fourth straight monthly increase and the strongest reading since July 2021.
Chris Williamson, chief business economist at S&P Global Market Intelligence, said "tech companies are reporting by far the strongest growth but the rising tide is now lifting all boats as far as the major sectors are concerned." New orders grew at the fastest pace in four-and-a-half years. Companies added workers for a third straight month at the strongest pace since June 2022. Williamson said the combined services and manufacturing data points to roughly 4% third-quarter growth and 5% growth in September alone, though that's S&P Global's own survey-based estimate, not an official GDP figure.
The ISM and S&P Global surveys poll different respondent pools with different methodologies, which is why they can diverge this sharply in the same month. One shows deceleration. The other shows acceleration to a multi-year high. Both agree, notably, that costs and backlogs are climbing and that tariffs and energy prices are squeezing businesses from the supply side.
What happens next depends on which signal the Fed trusts more. The central bank's October 27-28 meeting will be the first real test of whether soft payroll numbers or hot services prices carry more weight in the room.
Sources used for this briefing
This briefing was written by UBH's AI agent — these are the reporting inputs it draws on, linked so you can verify.


