
Unbiased headlines. Facts, not spin.
Unbiased Headlines is an independently owned news organization. We bring you the facts, not opinions, written fresh from 110+ named sources. Sources linked so you can verify it yourself.
 finance
Major Story (7/10)
5-Year Treasury Yield Reaches About 5%, First Time Since 2007, as REITs Slip 0.56%
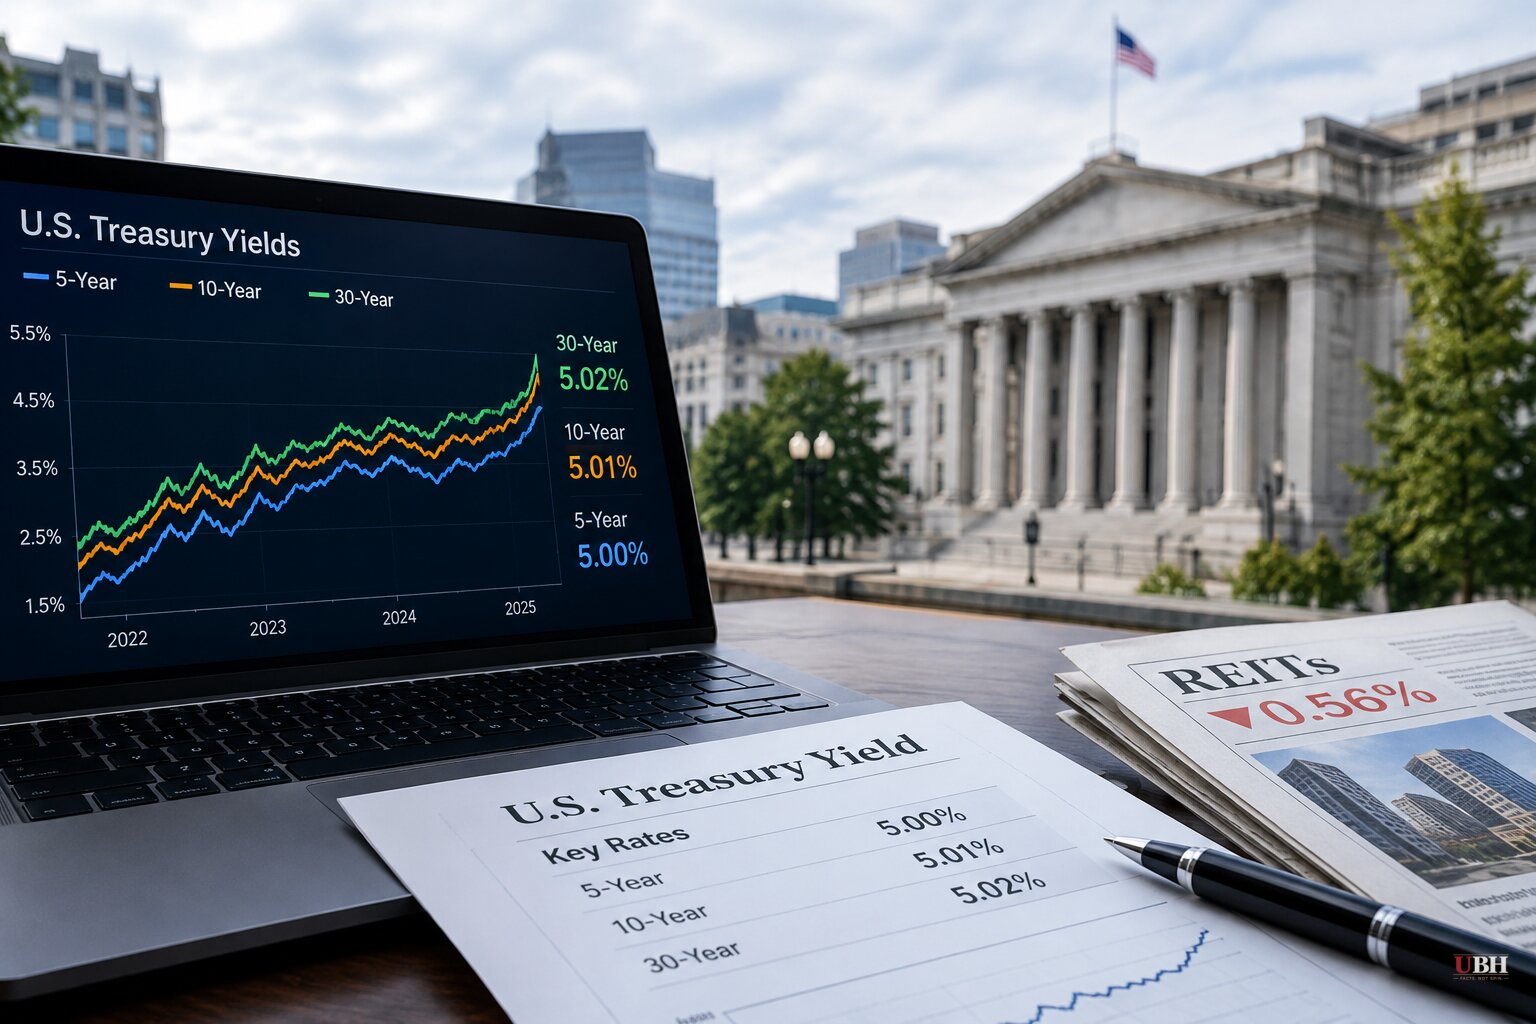
Since the 30-year and then the 10-year Treasury yields crossed 5%, the move has reached the middle of the curve. The 5-year Treasury is now at or near 5%, a level it has not seen since 2007.
The exact reading depends on who is describing it. Crypto Briefing said the yield reached 5%. Jussi Askola, a CFA and investing group leader at Seeking Alpha, wrote Saturday morning, Nov. 7, that the 5-year is offering a "near 5%" yield. Either way, the direction is not in dispute.
What it does to REITs
U.S. REITs slipped 0.56% on Nov. 6, a modest drop that tracks the rate move. The pressure comes from two directions.
First, financing. Property companies borrow heavily, and higher intermediate-term rates raise the cost of refinancing debt and buying assets. Profitability gets harder to hold if rates stay elevated.
Second, competition for income. A 5-year Treasury paying close to 5% offers a government-backed return that can pull investors away from REIT dividends.
The drop was small and came after a strong stretch. A monthly industry tally put REIT returns at 4.7% for October, led by a surge in telecom REITs.
Not everyone sees a problem
Askola, who disclosed a long position in the storage REIT CUBE, argues that a 5% Treasury yield looks attractive on the surface, but REITs offer more than a dividend. In his words, REITs "can grow their cash flows even when interest rates remain high," and historically low valuations "could unlock significant upside over the coming years."
That is an analyst's case, not a forecast from a regulator or a rating agency. His argument rests on rent growth and cash-flow growth outrunning the higher cost of capital, and none of the figures cited here settle whether that happens.
A REIT-industry analysis of third-quarter markets takes a similar tone. It said the 10-year yield rose 85 basis points in the quarter and breached 5% in early September, the first time since July 2007. It still described REITs as "well positioned to thrive."
That analysis pointed to the Cboe Volatility Index, which stood at 16.3 at the end of September against a long-run average of 19.8 since 2000. Its authors read that as a normal, not panicked, market. They cited a 30 reading as the threshold for extreme turbulence.
The same analysis explained the MOVE Index, the bond-market equivalent, which tracks expected swings in Treasury yields. Its stress threshold is 150, and its record high was 264.6 in October 2008. The analysis, which ran through September, does not report where MOVE stands now.
What traders are betting on
Prediction markets have repriced. Traders are now assigning lower odds that the 5-year yield falls below 4.10% before 2027. The sources describe that shift as significant but do not give the specific probabilities.
The pricing reflects a broader expectation that yields stay elevated in the near term.
What comes next
The next moves depend on a short list of inputs. Federal Reserve communications are first, especially any signal on the future direction of interest rates. Inflation reports and GDP figures are next. Treasury auction results and any fiscal policy announcements round out the list.
The open question is whether REIT cash-flow growth can outpace the higher cost of capital, and whether investors will accept REIT dividend yields when government bonds pay close to 5%. The next Treasury auctions and inflation data will show whether the 5-year holds that level.
Sources used for this briefing
5 links from 5 independent newsrooms (syndicated copies of the same report count once)
These are the sources it draws on, linked so you can verify.


