
Unbiased headlines. Facts, not spin.
Unbiased Headlines is an independently owned news organization. We bring you the facts, not opinions, written fresh from 110+ named sources. Sources linked so you can verify it yourself.
 economy
Notable (5/10)
Event date: November 2, 2026 ·
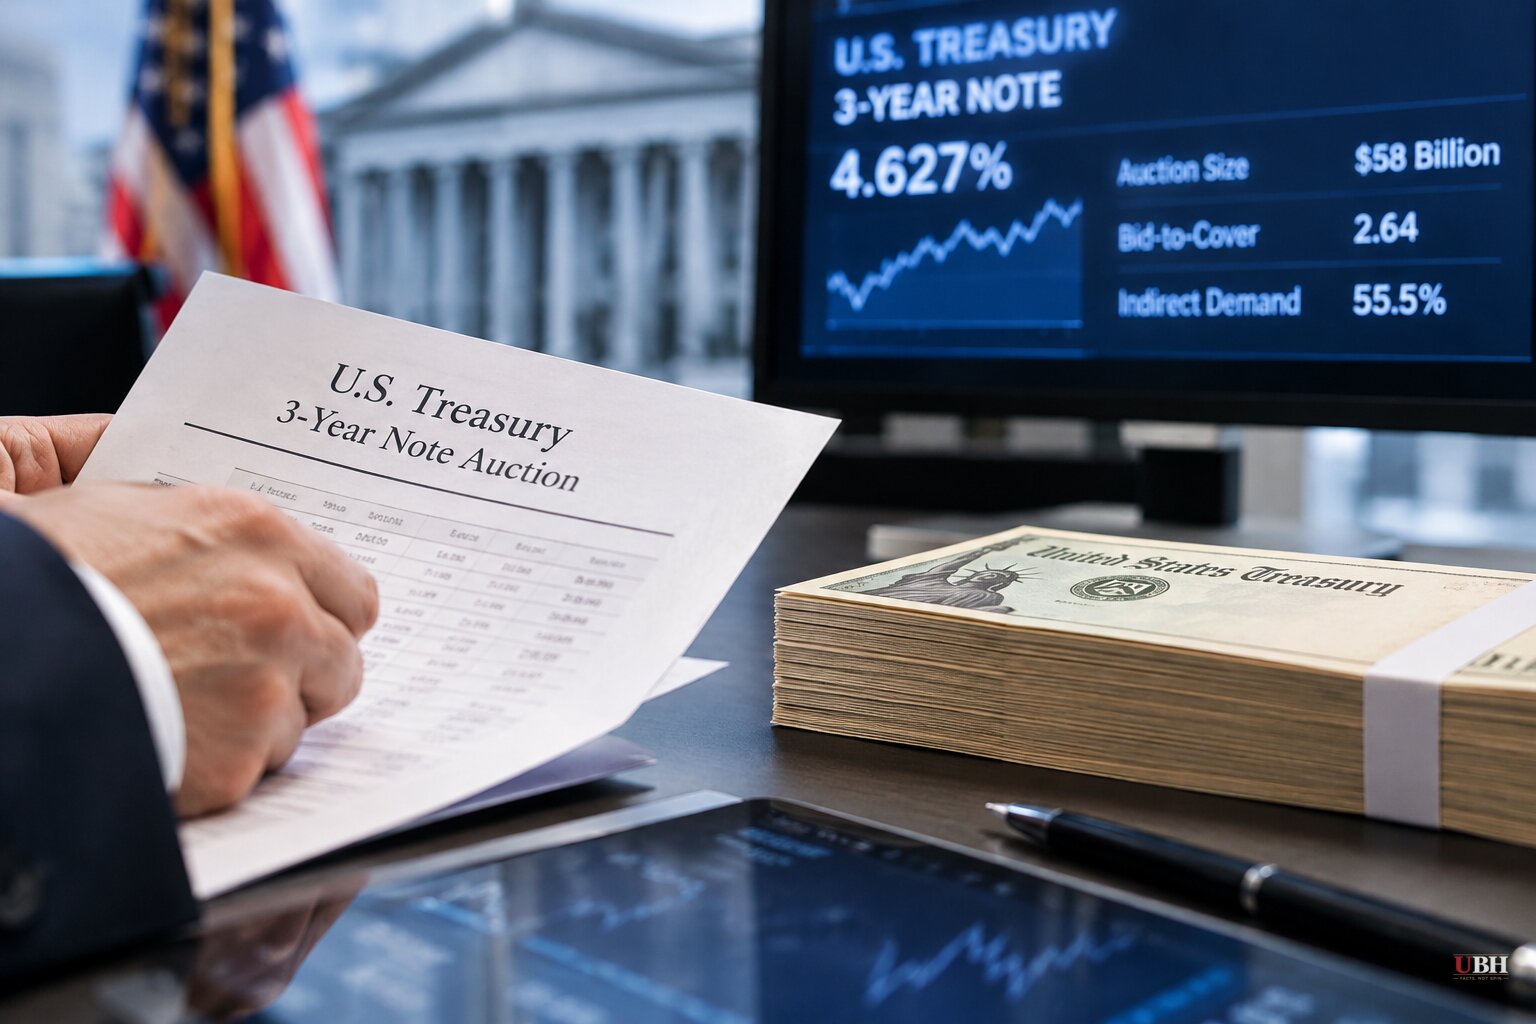
Treasury's $58 Billion 3-Year Auction Tails by 0.5 Basis Points as Indirect Demand Falls to 55.5%
Since Treasury dropped the words "at least" from its refunding guidance on Wednesday, Nov. 4, the market has been watching for any sign of how much appetite there is for new government paper. Today, Nov. 9, it got a data point. The $58 billion 3-year note auction was soft.
The auction
The high yield came in at 4.627%. That was 0.5 basis points above the when-issued level of 4.622%, a tail, and the largest since May. Last month's 3-year sale priced at 4.932% and stopped through its when-issued level.
The bid-to-cover ratio fell to 2.528 from 2.616 in October. That is the lowest since August 2025.
Indirect bidders, a category that includes foreign buyers, took 55.5% of the sale, down from 57.6% last month. That also is the lowest since August 2025.
Direct bidders took a record 35.04%. Primary dealers were left with just 9.5%, one of the lowest shares on record.
The sale was held on an accelerated schedule because Veterans Day falls on Wednesday, Nov. 11, when the cash bond market is closed.
What the numbers do and do not show
A half-basis-point tail is small. The high yield of 4.627% was below October's 4.932%, which ZeroHedge noted was the second highest this decade. Record direct participation, which is typically domestic investors, meant dealers were left with only 9.5% of the sale.
ZeroHedge called it a "clearly subpar auction" and argued that the slide in bid-to-cover and indirect demand suggests short-end paper has become "notably more challenging" to sell than in recent months. Crypto Briefing described the tail as modest but said the drop in foreign participation may point to broader concern about demand for U.S. debt. Both are interpretations. One auction is one auction, and indirect share is an imperfect proxy for foreign demand.
What is measurable: the 3-year note cleared with less indirect demand and a weaker bid-to-cover than in October, and direct buyers filled the difference.
Treasury's wording change
On Nov. 4, Treasury altered its forward guidance on auction sizes. It dropped "at least" and said it expects to keep floating-rate note and coupon auction sizes unchanged "for the next several quarters." Many analysts read "several" as two quarters, which would put possible changes in the first half of 2027, according to the reporting on the statement.
The 20- and 30-year auctions, which have at times struggled to draw demand, are seen as the most likely to be cut. Any coupon increases would probably land in the 2- to 7-year sector, possibly in 10-year notes. Treasury also said it will convert the 7-year note into a quarterly auction with two reopenings. It kept the 30-year bond auction at $25 billion, the same as in the May and August refundings.
The statement followed a bruising bond selloff last month that pushed 10- and 30-year yields to their highest levels since 2002, according to the reporting on the refunding.
Not everyone expects cuts to long-dated debt. The reporting on the refunding notes that Treasury may struggle to reduce auction sizes if its funding needs grow faster than expected. Treasury itself said it will evaluate changes based on structural demand trends and the costs and risks of various issuance profiles, and that it will seek financing at the lowest cost over time.
Volume keeps setting records
Treasury sold $839 billion through 11 auctions in the week of Oct. 26-30, a record for a single week, according to Tony Farren, managing director of rates sales and trading at Mischler Financial Group. The prior record was $795 billion, set in the same week a year earlier.
Most of that was rollover of maturing bills. Net new borrowing was $68 billion, far below the roughly $350 billion peak in a single week during the pandemic in spring 2020. The record was in gross issuance, not net borrowing.
Politics and the yield outlook
After the Democratic sweep in the midterm elections, analysts quoted by SCMP said a divided government may restrain future Treasury borrowing and limit fresh deficit blowouts. The same analysts said it will not necessarily bring yields down. They pointed to inflation, energy prices and AI-related spending as forces keeping yields elevated.
The 3-year was the first coupon sale of a holiday-shortened week. Treasury said it will sell $125 billion this week, including $58 billion in 3-year notes, $42 billion in 10-year notes and $25 billion in 30-year bonds. If indirect participation stays near this level in the 10- and 30-year sales, today's result will look like a trend rather than a blip. The next test of the "several quarters" guidance comes at the next quarterly refunding, when Treasury will say whether the 20- and 30-year auction sizes, and the 2- to 7-year sizes, are changing.
Sources used for this briefing
6 links from 5 independent newsrooms (syndicated copies of the same report count once)
These are the sources it draws on, linked so you can verify.


