
Unbiased headlines. Facts, not spin.
Every story is an unbiased news briefing written from 110+ sources across the spectrum — sources linked so you can verify it yourself.
 finance
Notable (6/10)
Event date: September 16, 2026
PBOC to Drain $8.4 Billion in Offshore Yuan Wednesday as China's Domestic Loan Growth Hits Record Low
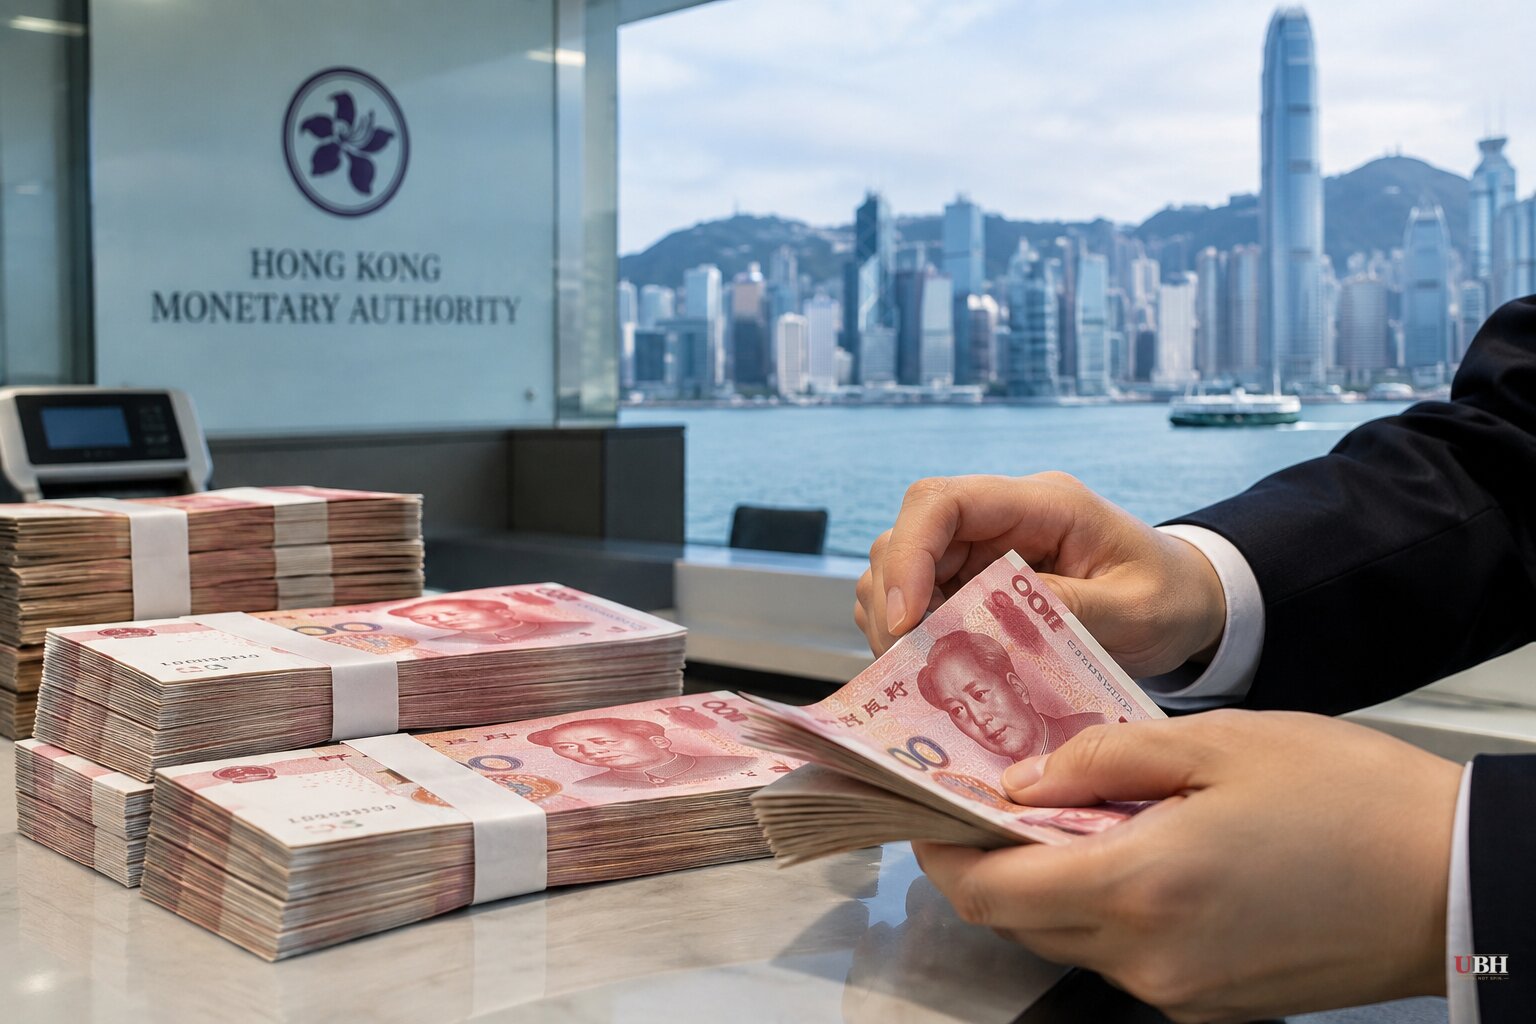
The People's Bank of China will issue 60 billion yuan, roughly $8.4 billion, in six-month bills through the Hong Kong Monetary Authority's Central Moneymarkets Unit on Wednesday, September 23, according to a press release the HKMA is scheduled to publish on September 21. It's a routine tool Beijing has run since 2018 to manage the offshore yuan, known as CNH, from outside the mainland's borders.
The mechanism is simple. When the PBOC sells bills in Hong Kong, it pulls yuan out of offshore circulation. Less supply means tighter funding conditions for anyone trying to bet against the currency, according to Newsquawk, which noted the effect typically shows up first in forward points and overnight deposit rates rather than the daily spot fix. Larger tranches signal a more aggressive drain. Routine rollovers of maturing paper are closer to neutral.
This isn't Beijing's first rodeo. Similar issuances hit in January 2025 and March 2026, according to Crypto Briefing, and past offerings in the 1.29% to 1.48% rate range have been oversubscribed every time. Offshore yuan lending in Hong Kong reached 935 billion yuan in 2025, and dim sum bond issuance, yuan debt sold outside the mainland, topped 1 trillion yuan for the year.
The backdrop: credit demand at home is falling apart
The timing matters. China's central bank data show new yuan loans in August came in at just 60 billion yuan, according to Reuters calculations reported by The Standard. Analysts had forecast a rebound to 400 billion yuan after a record 340 billion yuan contraction in July. Instead the bounce landed at a fraction of that, well below the 590 billion yuan booked a year earlier.
Zoom out and the trend gets worse. New loans totaled 10.44 trillion yuan for January through August 2026, down from 13.46 trillion yuan over the same stretch last year, The Standard reported. Outstanding yuan loans grew just 4.9% year-over-year in August, the weakest pace on record, slowing from 5.1% in July.
Beijing isn't sitting still. Policymakers expanded loan interest subsidies for small firms and consumers, injected $54 billion into eight state-owned financial institutions to shore up their capital, and extended maximum mortgage terms from 30 to 40 years to ease homebuyer repayment burdens, according to The Standard. Analysts quoted in that report remain cautious about whether any of it revives housing demand.
PBOC Governor Pan Gongsheng addressed the slowdown directly in an essay published in the Communist Party's theoretical journal, reported by the South China Morning Post. "Maintaining past credit growth rates is difficult and unnecessary," Pan wrote, arguing that reviving inefficient existing loans is essentially equivalent to issuing new credit. He framed the slowdown as part of a deliberate shift away from real estate and infrastructure toward high-end manufacturing and green industries.
The yuan internationalization pitch runs into its own data
China's government has spent years pushing the yuan as a dollar alternative, and there's a case to be made that progress is real. Xi Jinping called in 2023 for China to become a "strong financial country" with a currency carrying "status as a global reserve currency." Pan himself warned in 2025 that a dominant global currency "tends to be instrumentalized or weaponized," according to the Peterson Institute for International Economics. China's Cross-Border Interbank Payment System, CIPS, has seen a wave of global banks sign on, and its growth accelerated further during the Strait of Hormuz crisis.
That's the strongest version of the bull case, grounded in real signups and real volume growth on CIPS.
But Martin Chorzempa of the Peterson Institute lays out the countervailing data. Yuan-denominated volume on Hong Kong's CHATS system, which handles three times the payment volume CIPS does, has plunged since mid-2024. The yuan's share of SWIFT payments has fallen from its mid-2024 peak and now sits behind the Canadian dollar as the world's sixth most-used payments currency. Meanwhile 72% of China's own trade is still settled in other currencies, and the US dollar remains at historic highs in global FX payments. Chorzempa reads the CIPS-versus-SWIFT divergence as evidence Beijing is prioritizing sanctions-proofing over building a currency that competes with the dollar on the open market.
None of that requires taking sides on whether China's long-term strategy will work. The "yuan is dethroning the dollar" headlines that circulated after 2023 aren't holding up against the payments data two years later, per the Peterson Institute's own numbers.
What to watch after Wednesday
The tell will be CNH HIBOR fixings in the sessions right after the bill settles, plus the spread between the offshore CNH rate and the onshore CNY rate, according to Newsquawk. A widening gap would suggest depreciation pressure Beijing is still fighting. The bill sale also lands as the US and China hold dialogue ahead of a planned Trump-Xi summit, per Newsquawk's market notes, which means currency stability into that meeting is likely part of the calculation. Whether Beijing needs a follow-on tranche will be the next signal to watch.
Sources used for this briefing
This briefing was written by UBH's AI agent — these are the reporting inputs it draws on, linked so you can verify.


