
Unbiased headlines. Facts, not spin.
Unbiased Headlines is an independently owned news organization. We bring you the facts, not opinions, written fresh from 110+ named sources. Sources linked so you can verify it yourself.
 finance
Major Story (7/10)
Event date: October 25, 2026 ·
Fitch Puts US Private Credit Default Rate at Record 6.3%, With Most Defaults Coming Through Deferrals and Extensions
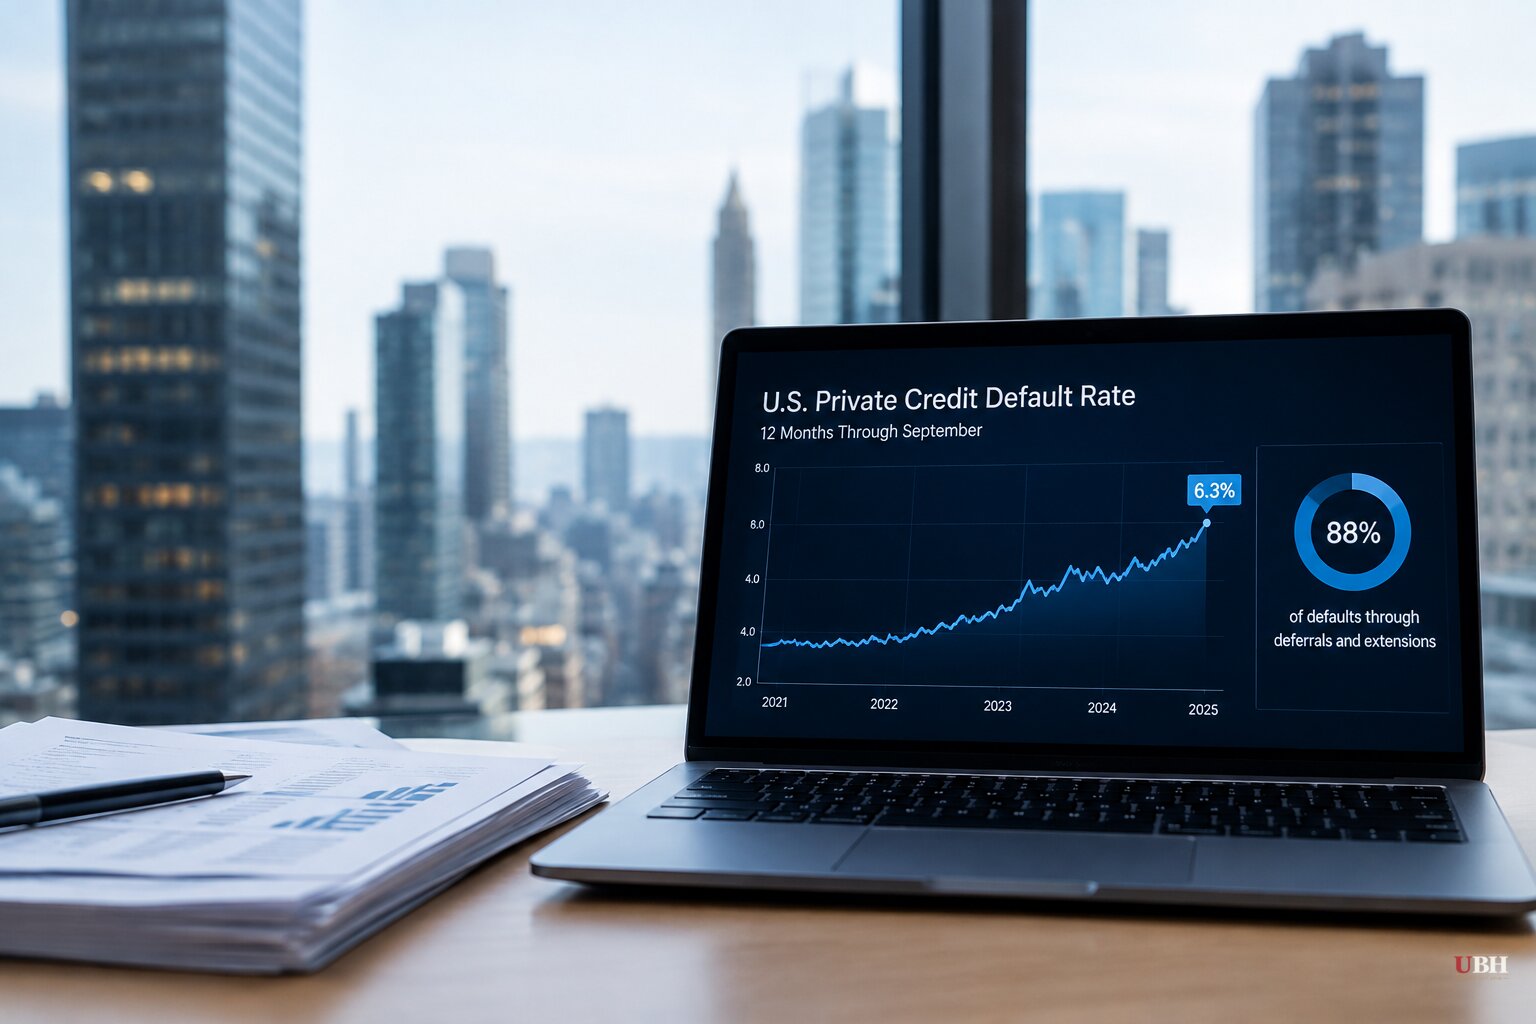
Since Fitch Ratings released its third-quarter private credit report last week, the headline number has drawn fresh attention: a record 6.3% default rate for the trailing 12 months ended in September.
That is up from 6.0% in the second quarter. It also matches the record monthly reading Fitch logged in August.
What Fitch counted
Fitch recorded 27 default events in the third quarter, involving 20 newly defaulting borrowers. The number of unique defaulters over the trailing 12 months reached 91, up from 84 the quarter before.
The makeup of those defaults is the telling part. In the third quarter, 13 events were interest deferrals or new payment-in-kind arrangements. Another 10 were stressed maturity extensions.
Only one event was an uncured payment default. Three were bankruptcies, liquidations or out-of-court restructurings.
Over the full 12 months, deferrals and payment-in-kind arrangements made up half of all default events. Stressed maturity extensions made up another 38%. That adds up to about 88% of defaults coming through negotiated changes to the loan, not a borrower simply failing to pay.
Where the stress is concentrated
Industrials and Manufacturing and Consumer Products and Services each posted a 9.7% default rate. Those were the highest among the largest sectors Fitch monitors.
Healthcare providers had the most unique defaulters over the year, at 16. The sector's default rate actually improved, falling to 8.7% from 9.4%.
Fitch's model-based credit opinion portfolio showed a default rate of 5.7%, up from 4.9%. Its privately monitored ratings portfolio went the other direction, falling to 8.0% from 9.4%. Fitch attributes part of that improvement to growth in the monitored portfolio, not just less distress.
The limits of the number
Fitch's figures cover its monitored private credit universe. They are not a default rate for every private loan in the United States.
The definition also matters. Counting a payment-in-kind switch or a distressed extension as a default captures trouble that a narrower bankruptcy-or-missed-payment test would miss. It also means a record reading does not translate into a record number of failed companies.
Moody's draws a similar line in its own work. Its analysis of middle-market borrowers found a reported default rate of 4% that rose to 5.8% once distressed debt exchanges were included.
The pushback and the warning
The case for caution comes from QTR, the author of the Fringe Finance newsletter, who has warned about private credit for two years. He calls the pattern "extend and pretend," arguing that lenders are letting borrowers defer interest, capitalize it into more debt or push out maturities to avoid recognizing losses. In his words, these arrangements "can keep companies technically operating while doing very little to fix the underlying problem: too much debt and not enough cash flow."
He also concedes the limits of that argument. The entire private credit market is not about to implode, he writes. Senior creditors have structural protections, and some borrowers will refinance or recover.
The restructuring-heavy mix can be read either way. It shows lenders are working with borrowers instead of forcing liquidations. It also shows how much distress is being managed through changed terms rather than resolved. Fitch's own data does not say which reading proves right, because many of these loans have not yet reached their final repayment tests.
The 2027 and 2028 refinancing window
The pressure point is timing. A large batch of private loans originated in the cheap-money years of 2020 through 2022 will need refinancing in 2027 and 2028. Many of those borrowers took on debt under conditions that no longer exist.
Moody's found that borrowers with deeply speculative credit profiles account for more than half of the debt coming due in those two years within its middle-market CLO sample.
That sample is Moody's, not the whole market. Whether those borrowers can refinance, or whether lenders extend again and take deeper losses later, will be tested starting next year. Fitch's fourth-quarter report is the next data point on whether the 12-month rate keeps climbing past 6.3%.
Sources used for this briefing
7 links from 5 independent newsrooms (syndicated copies of the same report count once)
These are the sources it draws on, linked so you can verify.


