
Unbiased headlines. Facts, not spin.
Unbiased Headlines is an independently owned news organization. We bring you the facts, not opinions, written fresh from 110+ named sources. Sources linked so you can verify it yourself.
 tech
Notable (6/10)
Broadcom Guides to $115 Billion in AI Chip Revenue for Fiscal 2027 While Its Stock Lags the S&P 500
Broadcom's AI chip business is growing at a pace few companies of its size have ever managed. Its stock has barely noticed.
CEO Hock Tan said on the company's latest earnings call: "In 2027, we have secured the supply to again double AI revenue to approximately $115 billion." Reports put the prior target for that year at more than $100 billion. Fiscal 2026 AI revenue is projected at about $58 billion, and the outlook reportedly stretches to $230 billion in fiscal 2028.
Broadcom's fiscal year ends in October, so the $115 billion figure covers the period through October 2027.
The numbers behind the target
In fiscal third quarter, AI semiconductor revenue hit $16.7 billion, up 221% from a year earlier. Total company revenue was $29.6 billion, up 86%. AI now makes up more than half of the total.
For the fourth quarter, Broadcom guided to AI revenue of $21.7 billion, up 236% year over year. Total revenue guidance of about $34.8 billion came in slightly under the $35.1 billion Wall Street was expecting, according to MoneyDJ.
The cash side is solid. Broadcom produced $13.7 billion in free cash flow in the quarter and raised its dividend 10% to $0.65 per share.
Tan also said demand from its largest hyperscale customers already exceeds Broadcom's initial outlook.
Who is buying
The business rests on custom accelerators, which Broadcom calls XPUs, and networking components. Anthropic, OpenAI, Google and Meta all use Broadcom hardware in parts of their AI infrastructure.
Tan expects Anthropic to become Broadcom's largest XPU customer in 2027. Broadcom has also participated in Anthropic's private placement as a strategic investor. Yahoo Finance reported that Anthropic plans to deploy 5 gigawatts of Broadcom-built TPUs in 2027, while OpenAI's Jalapeno chip targets 1.3 gigawatts.
Tan has argued the custom approach wins on performance: "When you co-develop a chip that is optimized for your particular large language model workloads, you will outperform any GPU."
A stock that has not followed
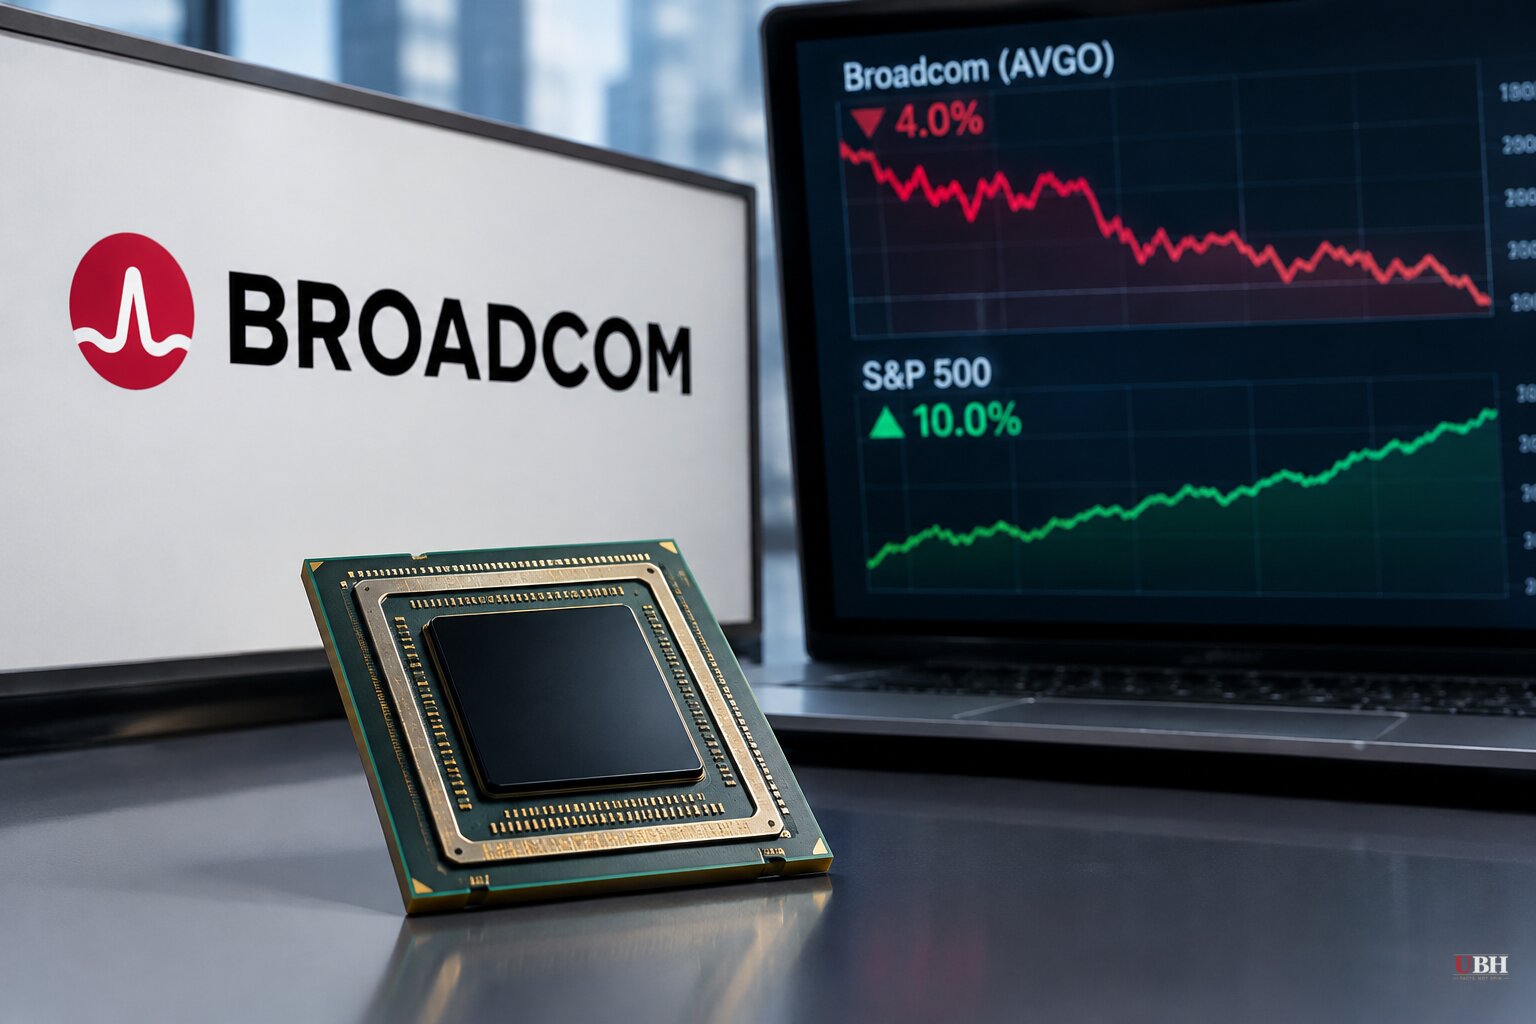
Shares are down about 4% year to date, while the S&P 500 is up about 10%, per Motley Fool data. The 52-week range runs from $289.77 to $495.00. At the 4:00 p.m. ET close today, Nov. 19, the stock was down 2.09% on the day, with a session range of $345.00 to $369.26 and a market cap of roughly $1.69 trillion.
The picture is volatile. Yahoo Finance noted the stock gained 18.16% in the week before Nov. 16, and TIKR calculates it still sits about 26% below its June 2 closing high.
Wall Street is mostly bullish. Of 51 analysts tracked by 24/7 Wall St., 8 rate it Strong Buy, 41 Buy and 2 Hold. The average price target is $529.24. Consensus fiscal 2027 revenue is $175.5 billion, with EPS of about $19.47.
On those estimates, the stock trades at roughly 18x to 20x forward earnings, depending on the source. A Seeking Alpha contributor, Fountainhead, who discloses a long position, calls that a bargain for a company growing around 66%.
The skeptics
There are real objections. The Motley Fool's Prosper Junior Bakiny, who is nonetheless bullish, says guidance has been "somewhat disappointing" in recent quarters and that fast AI growth could pull gross margins down relative to the higher-margin infrastructure software segments. Investors also remain wary of the semiconductor cycle.
The sharper concern is customer concentration. TIKR's analysis says Broadcom now guarantees two rounds of rack leases by Anthropic, capped at $29 billion and about $43 billion. That totals roughly $72 billion, three times the $24.0 billion in cash Broadcom held as of Aug. 2.
TIKR cites that exposure as a major reason Rothschild & Co Redburn downgraded Broadcom to Neutral on Nov. 13 and cut its price target.
A Reddit user on r/ValueInvesting, quoted by TIKR, put the valuation question another way: at about 45x trailing earnings the stock is "not a value multiple by any definition." The bull reply is that earnings are growing so fast the multiple compresses on its own. Analysts expect normalized EPS to nearly triple, from $6.82 in fiscal 2025 to $19.41 in fiscal 2027.
The math also leans heavily on AI. Subtract Tan's $115 billion from the $175 billion revenue consensus and about $60 billion is left for everything else, which TIKR notes is more than that business generates this year.
What comes next
Marvell reports on Dec. 1. Broadcom follows on Dec. 9 with its fiscal fourth-quarter results. Hitting the $21.7 billion AI revenue guide would keep the company on pace for its roughly $58 billion fiscal 2026 figure. A miss would put the $115 billion target, and the Anthropic lease guarantees behind it, under immediate scrutiny.
Sources used for this briefing
7 links from 7 independent newsrooms (syndicated copies of the same report count once)
These are the sources it draws on, linked so you can verify.


