
Unbiased headlines. Facts, not spin.
Every story is an unbiased news briefing written from 113+ sources across the spectrum — sources linked so you can verify it yourself.
 finance
Notable (5/10)
October 1, 2026 at 03:14 AM
Swiss National Bank Official Warns Stablecoins Could Weaken Its Grip on Interest Rates
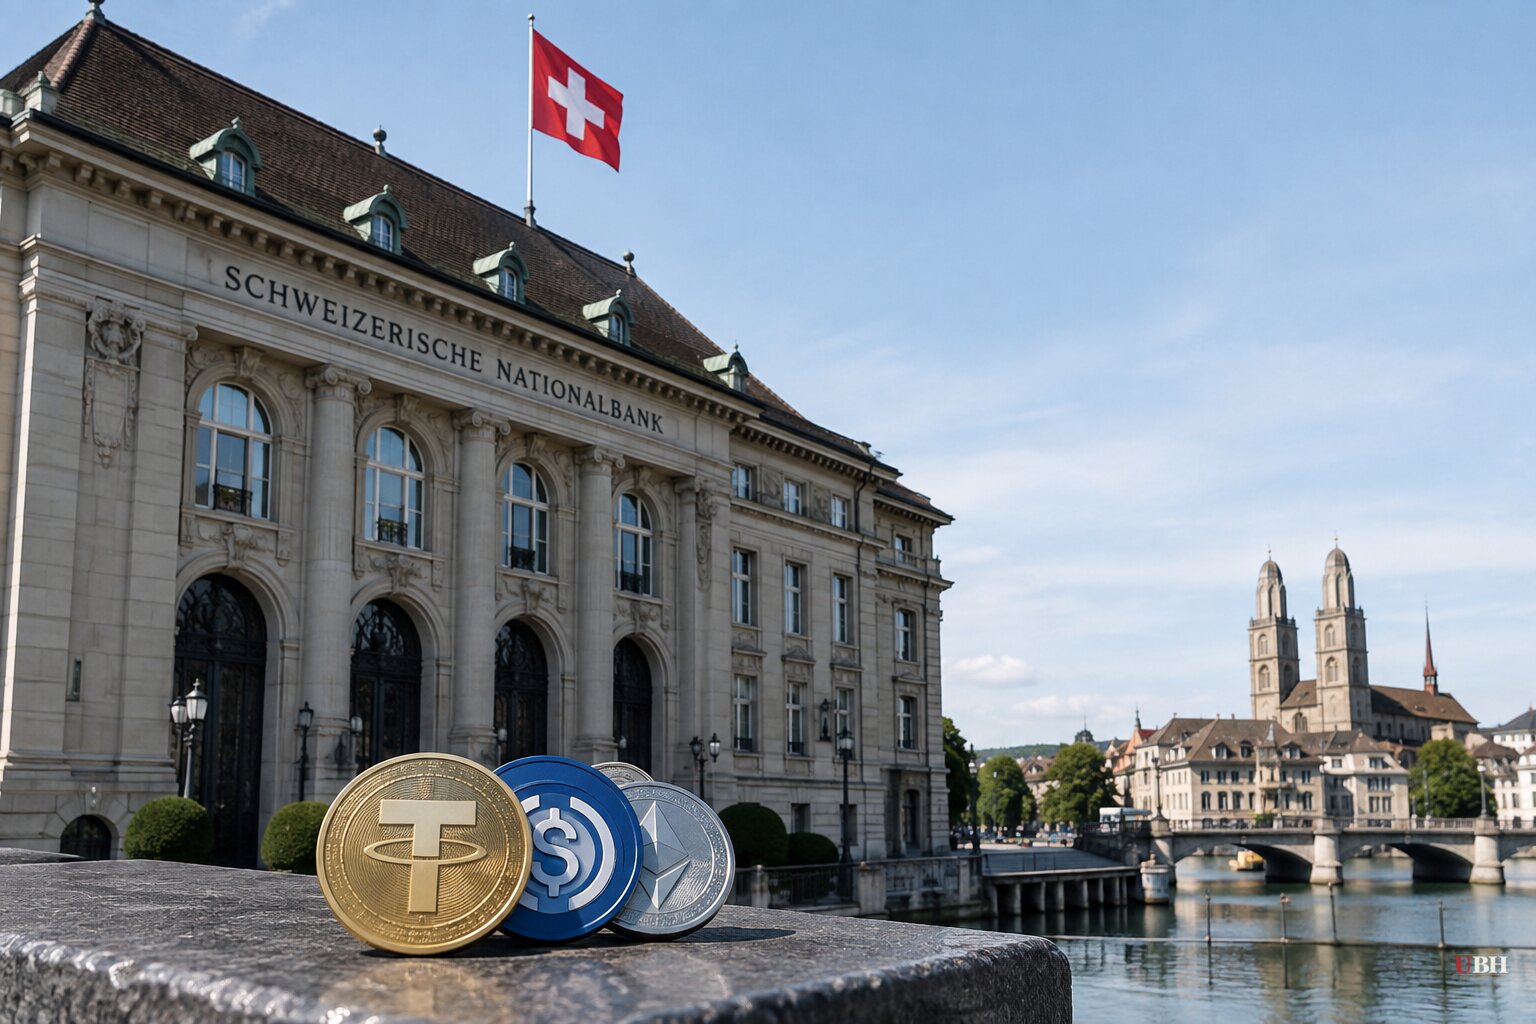
The Swiss National Bank has found a new thing to worry about, and it's not inflation or the franc's exchange rate. It's stablecoins.
Speaking at an event in Zurich on Wednesday, September 30, 2026, SNB Governing Board member Petra Tschudin said large stablecoins could make it harder for the central bank to do its job, according to Reuters reporting carried by AOL and Global Banking and Finance Review. Her specific worry: monetary policy transmission, the mechanism by which a central bank rate move eventually shows up in what you pay for a mortgage or a business loan.
"When we introduce innovations, we really need to ask what consequences they have, and how they should be regulated," Tschudin told the Zurich audience, per Reuters.
How the SNB Says It Works, and Why Stablecoins Worry Them
Central banks operate what's called a two-tier financial system. The SNB sets policy and deals with commercial banks. Those banks then deal with households and businesses, passing along the rate changes.
Tschudin's argument is that stablecoins sit outside that structure. "If we end up with big stablecoins that are really far removed from the existing two-tier financial system, then that's a situation which increases the burden on central banks in fulfilling their mandate," she said, according to Reuters.
She raised two distinct problems. First, a "stablecoin franc" isn't automatically worth the same as an actual franc, since it sits outside the central bank system, undermining what she called the principle that money should be uniform everywhere. Second, if households and businesses move deposits out of commercial banks and into stablecoins, banks have less to lend, which blunts the SNB's influence over interest rates.
"We have an effect on how much credit, or how expensively credit is made available in the economy, and that naturally has knock-on effects for monetary policy," Tschudin said. "So if we see this effect, we get a certain disruption to the transmission mechanism."
Tschudin didn't call for banning the technology. She acknowledged stablecoins can modernize payments, including by cutting the cost of international transfers, and said the SNB "welcomed innovation," per Reuters. Her ask was regulation, not prohibition.
The Actual Risk, Not Just the Turf Battle
There's a real consumer-protection case buried in here, separate from the central bank's self-interest in keeping its hands on the levers. The SNB's July 2026 financial stability report flagged run risk: a stablecoin backed by inadequate reserves could face a wave of redemptions it can't cover, according to Crypto Briefing. That's not a hypothetical. It's the same structural vulnerability that has sunk poorly collateralized stablecoins before. Demanding real reserves and real audits for anything marketed as a dollar-for-dollar or franc-for-franc substitute isn't central-bank turf protection, it's basic truth-in-advertising for money.
The broader complaint, that stablecoins might pull deposits out of the banking system and weaken the SNB's grip on borrowing costs, is a different animal. That's a central banker admitting that private, voluntary alternatives to government-controlled money could actually compete with it. Americans and the Swiss alike have heard this complaint before about everything from gold to foreign currency to crypto generally: if people have better options, they might use them, and that's treated as a problem for the institution that wants to control the money supply rather than a problem for the public.
The Numbers Don't Match the Alarm, Yet
The SNB's own July 2026 report found the market for Swiss franc stablecoins was under $50 million as of mid-2026, according to Crypto Briefing. The central bank itself judged domestic risks "manageable for now."
So the warning on September 30 is about a future scenario, not a current crisis. Switzerland isn't waiting around regardless. Lawmakers are creating a new license category, called a payment instrument institution, for fiat-backed stablecoin issuers, under amendments to the Financial Institutions Act, Crypto Briefing reported. The SNB is also running its own alternative, Project Helvetia III, a wholesale central bank digital currency experiment.
What's Unresolved
The open question is whether Switzerland's new licensing regime ends up being proportionate consumer protection or a mechanism to keep stablecoin issuers permanently subordinate to the SNB's two-tier system. Tschudin didn't specify what the regulation would require beyond "guardrails," and no draft rules or enforcement timeline have been published yet. Whether Swiss regulators strike that balance, or tilt toward protecting the central bank's own turf, will play out as the Financial Institutions Act amendments move toward implementation.
Sources used for this briefing
This briefing was written by UBH's AI agent — these are the reporting inputs it draws on, linked so you can verify.


