
Unbiased headlines. Facts, not spin.
Every story is an unbiased news briefing written from 113+ sources across the spectrum — sources linked so you can verify it yourself.
 finance
Major Story (7/10)
October 1, 2026 at 02:35 AM
Riskiest US Corporate Bonds Hit Distressed Levels Not Seen Since 2023 Banking Crisis
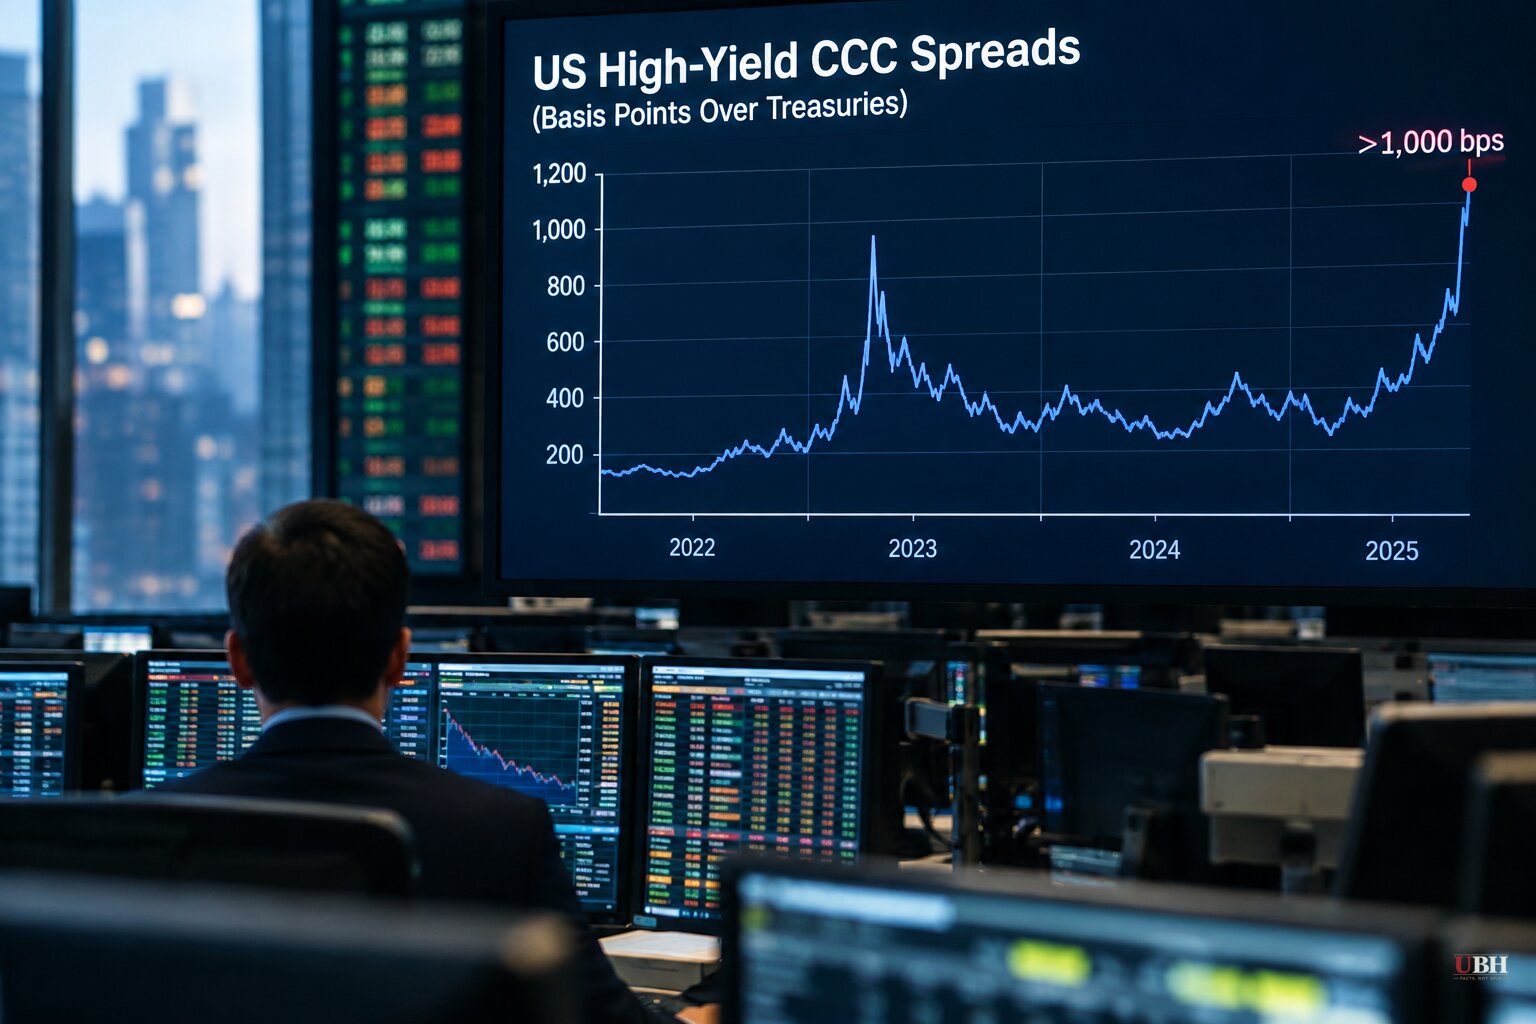
Since credit markets last flashed this kind of warning during the collapse of Silicon Valley Bank and Credit Suisse in March 2023, the bottom tier of the U.S. junk bond market has climbed back to the same danger zone this week.
The spread on CCC-rated corporate bonds, the lowest tier of junk debt, hit 1,007 basis points over Treasuries on Wednesday, according to Bloomberg. That's up from 860 basis points at the start of September. A risk premium above 1,000 basis points typically signals the market thinks default, restructuring or outright loss is likely.
Collin Martin, head of fixed income research and strategy at Charles Schwab Corp., told Bloomberg the driver isn't a recession scare. "The key driver is the economy is doing well but not necessarily going gangbusters," he said. "Triple C rated issuers are the riskiest issuers out there, and they tend to be the most sensitive to changing interest rates."
Bloomberg's own Markets Live strategist, Tatiana Darie, put it bluntly: "The junkiest names are selling off, reflecting concern that years of restructurings and kicking the can down the road on troubled debt will finally come home to roost as interest rates go up, triggering a fresh wave of defaults."
According to Bloomberg, CCC spreads have widened steadily since April as investors priced in the Federal Reserve tightening policy to fight inflation. Rising global yields hit highly leveraged borrowers two ways: debt service costs climb, and refinancing gets harder just as a wave of bonds and loans comes due.
Jack McIntyre, a global bond and fixed income portfolio manager at Franklin Templeton Inc., flagged a historical pattern worth watching: "Historically, when the Fed hikes into higher energy prices bad things happen to the economy."
Not All Junk Is Equal
Barclays Plc data cited by Bloomberg shows more than half of the worst-performing CCC bonds sit in technology, media and telecommunications, with cable and satellite companies leading the losses. Corry Short, a Barclays strategist, said the dispersion inside the CCC bucket is unusually wide right now. This isn't a uniform collapse across the ratings tier but rather concentrated in specific sectors and specific borrowers.
That distinction matters. A reasonable concern, raised implicitly by the comparison to 2023, is that a spike like this could be an early signal of a broader credit event, the same way SVB's failure cascaded through regional banks. But the Barclays dispersion data suggests something narrower: a sorting-out of the weakest credits rather than a system-wide liquidity freeze like the one that took down two banks three years ago.
The Price of 2021-Era Cheap Money
Apollo's chief economist, Torsten Slok, laid out the fuller picture in a research note dated September 22, 2026, cited by Kadenwood Group. CCC yields are now near 15%, even as the rest of the credit market stays calm. The Bloomberg index tracking Caa-rated U.S. high yield debt bottomed near 5% in 2021, sat around 10% at the start of 2026, and has climbed steadily since, roughly tripling off its cheap-money low.
Slok's September 22 note put the rest of the ladder at: money market funds 3.5%, 10-year Treasuries 5.0%, investment grade credit 5.7%, high yield overall 7.6%, and private credit 8.3%. CCC borrowers are now paying roughly double the broad high-yield average, a gap of about seven percentage points, according to the note.
Apollo's read is that monetary tightening is working, just unevenly. Companies with strong balance sheets locked in cheap fixed-rate debt years ago and have barely felt the squeeze. The most leveraged borrowers, many of them private-equity-backed companies in technology, healthcare and consumer discretionary with floating-rate debt and thin margins, are hitting the refinancing wall in full force.
Lincoln International found that 70% of the principal amount direct lenders foreclosed on in the first half of 2026 traced back to loans originated in 2021 and 2022, the peak of the zero-rate borrowing binge, according to the Kadenwood Group analysis of Apollo's research.
What's Different From 2023
The 2023 spike was driven by a sudden bank liquidity crisis after SVB and Credit Suisse failed, forcing a broad flight from risk. This episode, based on the sourcing here, looks more like a slower-moving reckoning: years of debt issued at rock-bottom rates during the 2021-2022 boom is now coming due into a world where the cheapest money costs 3.5% and the riskiest costs 15%.
The open question is whether that reckoning stays contained to the CCC tier, where Barclays says the pain is concentrated in TMT and cable names, or whether it spreads upward into the broader 7.6% high-yield market as more 2021-2022 vintage loans hit their refinancing walls in the months ahead. Neither Bloomberg, Apollo nor Lincoln International's data, as cited here, puts a dollar figure on how much of that vintage debt still remains outstanding.
Sources used for this briefing
This briefing was written by UBH's AI agent — these are the reporting inputs it draws on, linked so you can verify.


