
Unbiased headlines. Facts, not spin.
Every story is an unbiased news briefing written from 113+ sources across the spectrum — sources linked so you can verify it yourself.
 finance
Major Story (8/10)
September 29, 2026 at 05:33 PM
FICO Shares Post Worst Drop Since 2004 After FHFA Ends Fannie and Freddie's Reliance on Its Score Alone
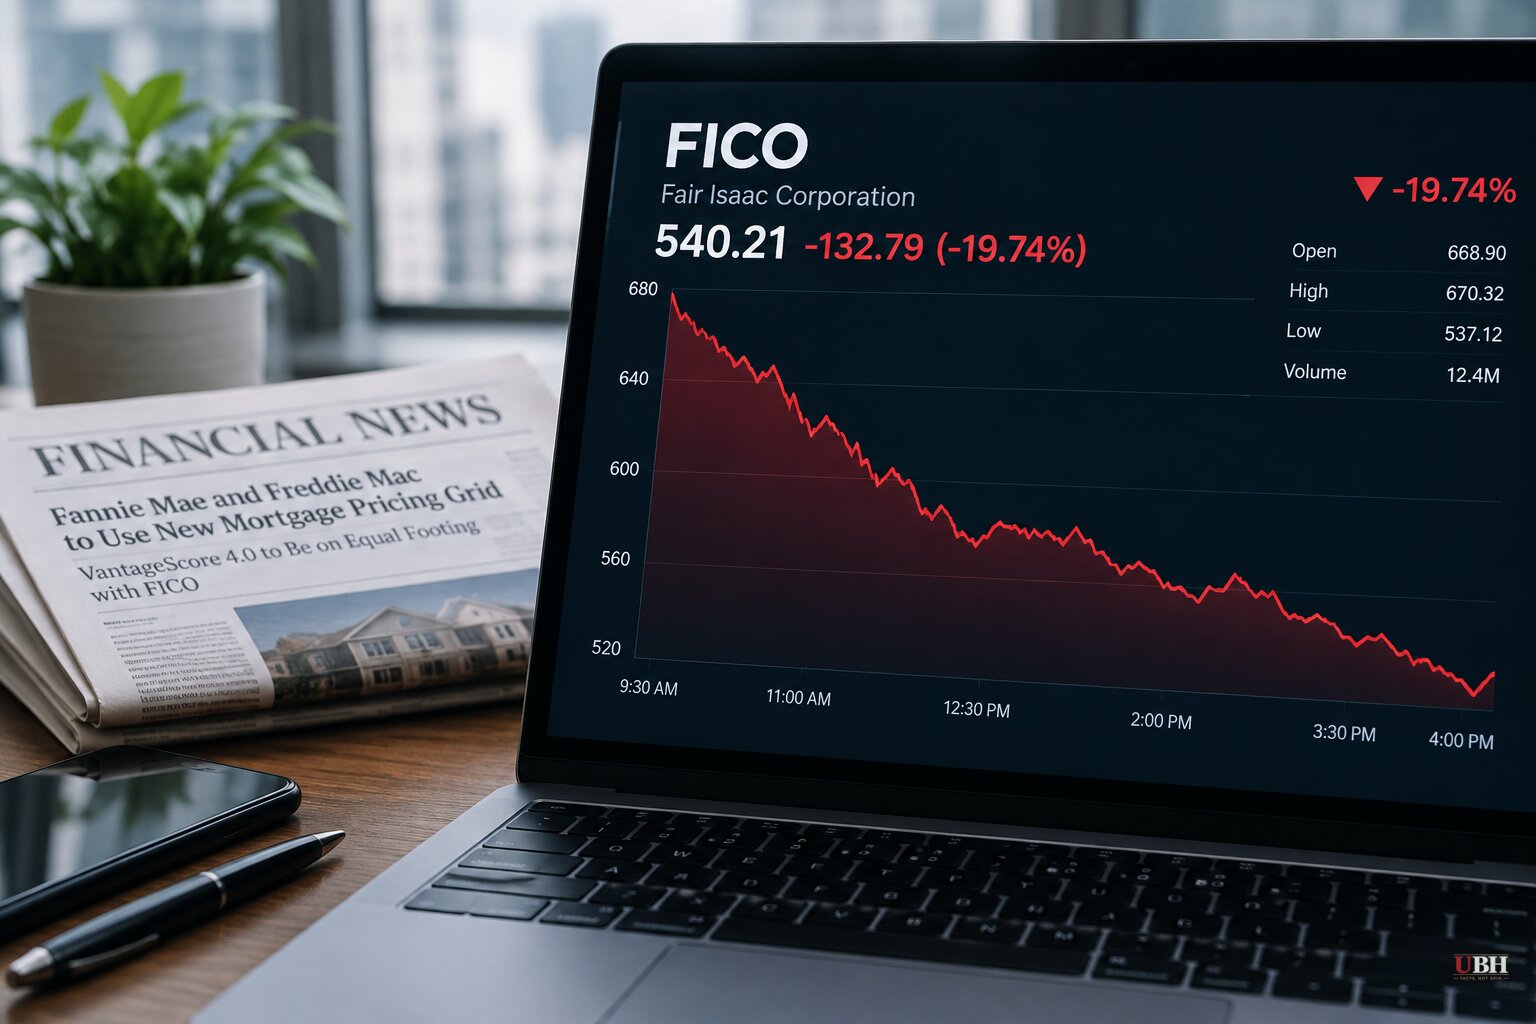
Fair Isaac Corporation lost roughly a fifth of its market value in a single trading session this week, and it started with a post on X from a federal regulator.
FHFA Director Bill Pulte announced Monday evening, September 28, that Fannie Mae and Freddie Mac will stop running two separate mortgage pricing grids and move to one. The change puts VantageScore 4.0, built and owned by credit bureaus Equifax, Experian and TransUnion, on the same pricing footing as FICO Classic for the first time. "We are Simplifying Mortgage Pricing following feedback from lenders and consumers," Pulte wrote, calling the old two-grid system one that "makes zero sense." According to Bloomberg Law, Pulte separately declared, "FICO has enjoyed a monopoly. No more."
That second line is Pulte's characterization, not a legal finding. No antitrust lawsuit, FTC complaint or formal investigation into FICO has been announced. The change also came through a social media post and a policy directive, not a completed rulemaking, and Yahoo Finance reported that FHFA has not specified a timeline for when lenders must adopt the new grid.
Why the Grid Matters
For two decades, a conventional loan sold to Fannie or Freddie required a FICO Classic score to calculate Loan-Level Price Adjustments, the risk-based fees baked into a borrower's rate, according to Yahoo Finance. Lenders had no real alternative. Under the unified grid, VantageScore 4.0 loses the roughly 20-point pricing discount it had carried against FICO and now competes directly on the same matrix, according to Deutsche Bank analyst Faiza Alwy, who told clients the shift means a higher share of loans will price favorably under VantageScore going forward. Alwy's blunt question to clients: "Where is the moat?"
Pulte pointed to a Rocket Mortgage announcement as validation. Rocket said its own study found VantageScore 4.0 "opens access to some clients who wouldn't be served otherwise," with borrowers who saved money under the model averaging $1,600 off at closing. Rocket has said it will make VantageScore 4.0 its preferred scoring model for eligible loans going forward.
Hours after Pulte's post, TransUnion said it will hold standalone VantageScore 4.0 mortgage pricing at 99 cents per score through December 2028, according to TradingView, giving lenders a multi-year price guarantee as they weigh switching away from FICO.
The Selloff, By the Numbers
Yahoo Finance reported FICO shares fell 8% in after-hours trading Monday night on the news. The damage came Tuesday: shares fell 20% in the pre-market session, according to TradingView, and ZeroHedge reported an intraday drop of 22%, calling it FICO's largest intraday decline since July 13, 2004. TradingView put the stock at $654.71 as of Tuesday, down 60.2% year-to-date and 65.2% below its 52-week high of $1,880, hit in October 2025.
This wasn't an isolated shock. TradingView noted FICO fell 15.2% roughly a month earlier when FHFA first approved VantageScore 4.0 for use by all lenders originating Fannie and Freddie loans. Tuesday's move built directly on that.
Not every analyst treated the news as fatal. Bloomberg-cited notes from FT Partners and TD Cowen flagged the risk to FICO's pricing power, but RBC maintained an outperform rating on the stock even after the crash, suggesting some on Wall Street still see value in FICO's decades of underwriting data and lender relationships even with VantageScore now on equal footing.
Fair Isaac has not issued a public statement responding to Pulte's announcement in the reporting reviewed here.
One Discrepancy Worth Flagging
Coverage of this story has not been entirely consistent. ZeroHedge and a separate wire account both describe Tuesday's drop as FICO's steepest since July 2004, a 22-year record. A separate report described the same move as the company's "steepest single-day decline in more than six years" and cited a 52-week high of $1,998.01 rather than the $1,880 figure TradingView reported. The 2004 comparison is corroborated by two independent accounts against one outlier, and is the more reliable read.
Pulte has also claimed FICO's per-score costs have risen roughly 1,800% cumulatively since 2020, a figure repeated by Investing.com and MarketScreener but not independently verified in FICO's own disclosures.
What's still unresolved: FHFA has not set a date by which lenders must actually implement the single grid, meaning the market reaction Tuesday priced in a policy shift that hasn't fully taken effect yet. Whether other major originators follow Rocket Mortgage's lead in preferring VantageScore, and whether FICO responds with its own pricing changes, will determine if Tuesday's crash was an overreaction or the start of a permanent shift in who controls mortgage credit scoring.
Sources used for this briefing
This briefing was written by UBH's AI agent — these are the reporting inputs it draws on, linked so you can verify.


