
Unbiased headlines. Facts, not spin.
Unbiased Headlines is an independently owned news organization. We bring you the facts, not opinions, written fresh from 110+ named sources. Sources linked so you can verify it yourself.
 health
Major Story (7/10)
Employer Family Health Premiums Reach $28,303 in 2026, With Workers' Share Up 9%
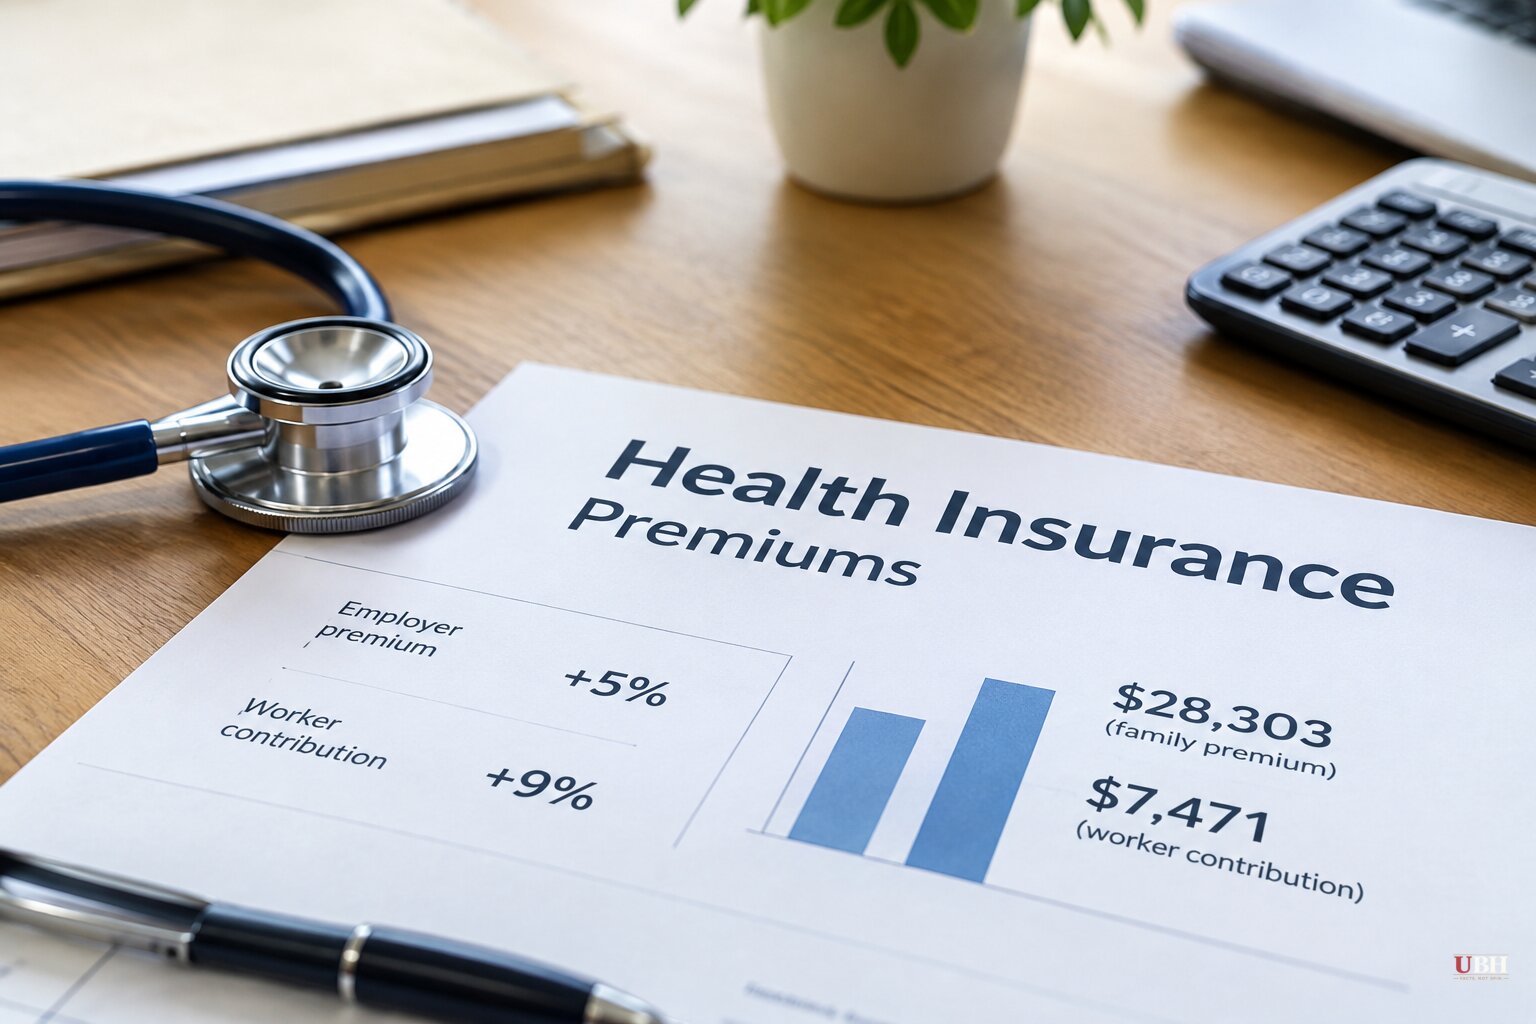
The average annual premium for employer-sponsored family coverage hit $28,303 in 2026, up 5%, or $1,310, from a year earlier. That comes from KFF's 2026 Employer Health Benefits Survey, released Thursday, Oct. 22. The survey drew on responses from 1,937 private and non-federal public employers with at least 10 workers.
Workers are carrying more of it. The average worker contribution for family coverage rose 9%, or $621, to $7,471. Employers paid the remaining roughly $20,800.
Wages rose 3.7% over the same period. General inflation was 2.7%.
Small businesses take the bigger hit
Workers at companies with fewer than 200 employees paid an average of $9,687 toward family premiums. Workers at larger firms paid $6,840, a gap of $2,847.
At small firms, workers cover an average of 37% of the family premium, compared with 25% at larger ones. Across all firms, the worker share ticked up only slightly to 27% for family coverage and 18% for individual coverage.
Deductibles follow the same pattern. The average individual deductible was $1,955 among workers with one, largely unchanged from $1,886 in 2025. At small firms it was $2,624, against $1,772 at larger employers.
The Small Business Administration says small businesses employ about 62.3 million people, or 45.9% of private-sector workers.
What employers are doing about it
Among employers with at least 200 workers, 44% said they raised the share of premiums employees pay. Another 21% raised deductibles or other cost sharing for most medical services. Employers also reported switching insurers, requiring prior approval for some services, and offering narrower networks of doctors and hospitals.
"When we start to see higher use or higher prices, there are only a limited number of things employers can do," said Matthew Rae, associate director of KFF's Program on the Health Care Marketplace.
The worker-contribution increase is also faster than last year's. KFF recorded a 7.6% rise from 2024 to 2025, followed by 9% this year.
Next year looks worse
Consultants expect more of the same. Aon projects employer health costs will rise 9.5% in 2027. Mercer estimates 8.2%. WTW forecasts 11.1%, which it says would be the largest increase in more than two decades.
The pressure is political too. An AP-NORC poll conducted in October found about 7 in 10 registered voters call health care "one of the most important issues" in the midterm elections. Almost 157 million Americans under retirement age get coverage through an employer.
President Donald Trump has made affordability part of his midterm pitch. He says his most-favored-nation prescription drug pricing would reduce costs, and he has promised rebates for some Americans. The Associated Press reported that other steps by his administration have raised costs for some people. The KFF survey does not show that drug pricing policy has yet changed what employers or workers pay.
Why big employers can't just fix it
Separate research from RAND and USC health researchers, published Nov. 1, argues that even large self-insured companies struggle to control costs. Self-insured plans cover two-thirds of the 165 million Americans who get insurance through work. In those plans the employer pays the medical bills directly.
For a decade, the federal response to rising employer costs has been price transparency, on the theory that companies that see prices can shop around. The researchers say interviews with employers, benefits consultants, claims administrators, and legal and policy experts led them to a different conclusion. In their words, "disclosure is not enough," and few outside the very largest employers can turn price information into leverage.
The obstacle is the third-party administrator, or TPA, which builds the provider network and processes claims. The researchers say the arrangement works when the TPA's incentives match the employer's, "but often they don't."
They point to "shared savings" fees. A legal expert gave a hypothetical: a provider bills $100,000, the TPA negotiates it down to $1,500, then charges the employer $30,000 for the discount. The employer sees a $31,500 claim. "I don't think they really tell you that $30,000 of that is a fee," the expert said.
Even with a fee breakdown, options are thin. National insurance carriers have bought up independent administrators and bundled specialty vendors into packages. Switching TPAs often means changing provider networks, which draws pushback from employees.
The experts cited by the researchers suggest contract terms that cap fees and require data access, transparency rules with real enforcement, and clearer rules on whether administrators share fiduciary duty with employers. They also note that enforcement resources tend to flow to employers big enough to demand them. A few employers have tried contracting directly with local hospital systems, moving to fully insured coverage, or sending workers to the ACA market with a defined premium contribution.
Whether any of those alternatives scales beyond a handful of employers is the open question. The 2027 forecasts from Aon, Mercer and WTW will test it as open enrollment decisions get made for the coming year.
Sources used for this briefing
7 links from 6 independent newsrooms (syndicated copies of the same report count once)
These are the sources it draws on, linked so you can verify.


