
Unbiased headlines. Facts, not spin.
Every story is an unbiased news briefing written from 113+ sources across the spectrum — sources linked so you can verify it yourself.
 finance
Notable (6/10)
September 22, 2026 at 08:45 PM
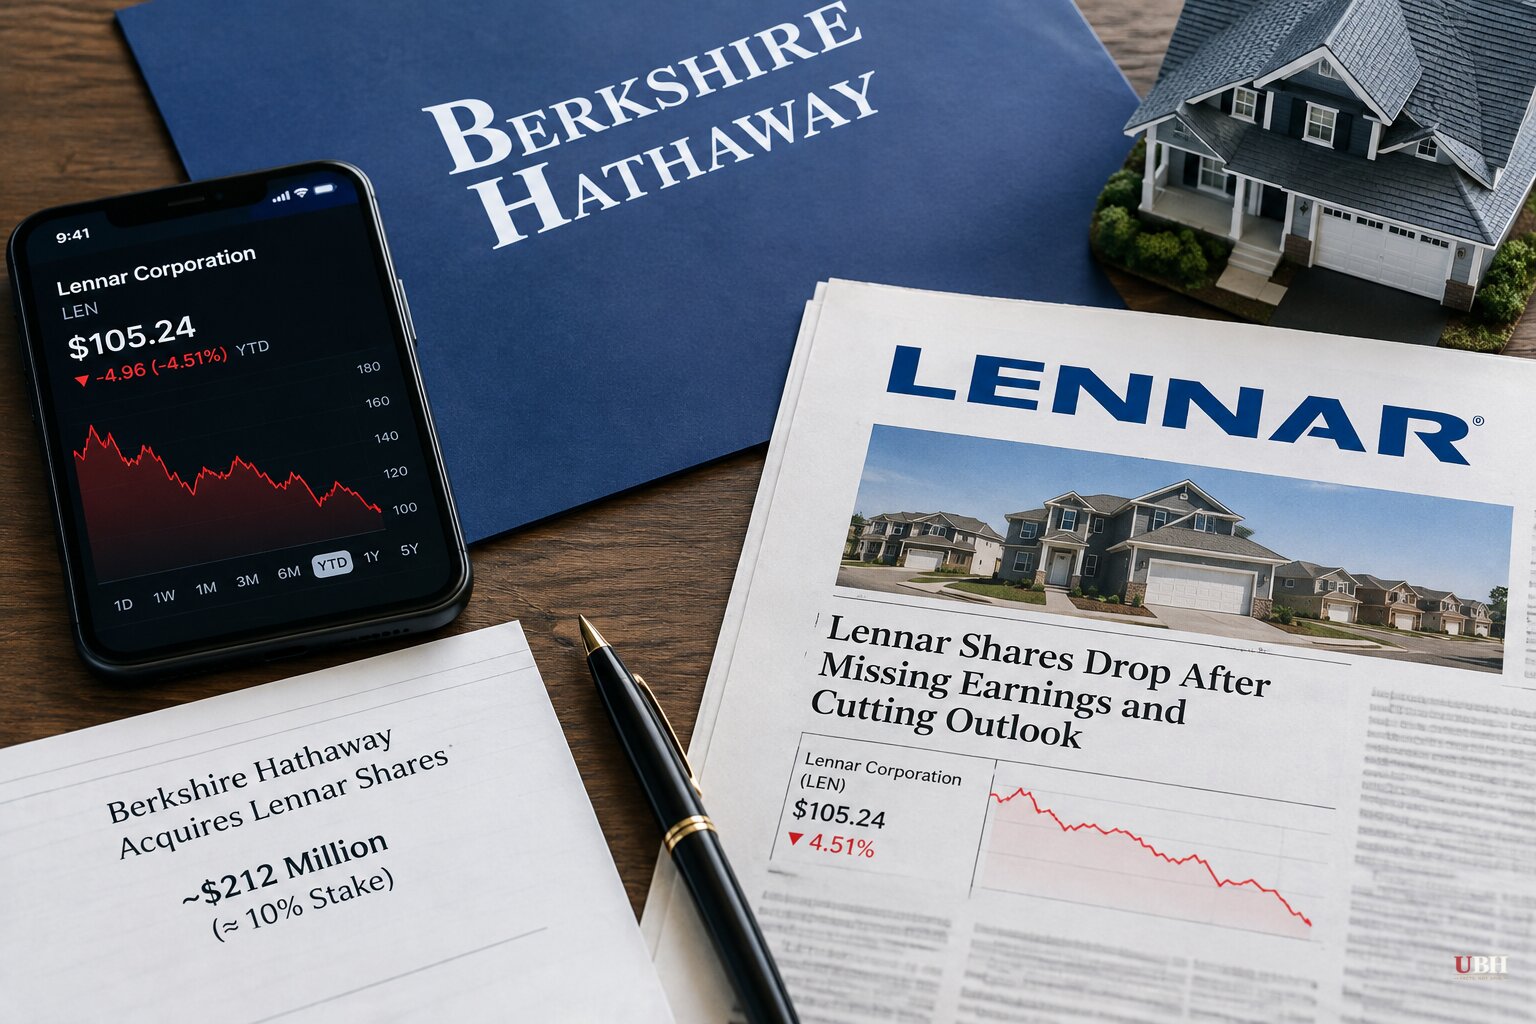
Berkshire Hathaway Builds Nearly 10% Stake in Lennar as Homebuilder Stock Slides 32% for the Year
Warren Buffett's old company just made a big bet on a stock that's down a third this year.
Berkshire Hathaway bought almost 2.7 million Class A shares of Lennar Corporation over three trading days ending Monday, September 21, according to a securities filing cited by CNBC. That brings Berkshire's total position to 23.7 million Class A shares worth about $1.8 billion. The Omaha-based conglomerate also holds 528,000 Class B shares, which carry 10 times the voting power of the Class A stock. MarketBeat put the three-day purchase price tag at roughly $212 million, lifting Berkshire's overall stake to just over 10%.
Lennar shares jumped as much as 6.6% on Tuesday, hitting a high of $83.24, after the filing became public. The Miami-based homebuilder is still down more than 32% over the past year.
Why Lennar Is Getting Hammered
The stock isn't down a third for no reason. Lennar reported fiscal third-quarter results last week, for the period ended August 31, and they were weak. Earnings per share came in at $1.23, missing Wall Street's consensus estimate of $1.29. Revenue fell 8% from the same quarter a year earlier.
Worse, Lennar's fourth-quarter guidance landed below expectations. On the earnings call, Lennar's leadership pointed directly at mortgage rates as the culprit, saying 30-year rates near 7% are shrinking the pool of qualified buyers and squeezing affordability.
The numbers back that up. Freddie Mac says the average 30-year fixed mortgage rate hit 6.95% last week, up from 6.76% the week before and 6.26% a year ago. The State Street SPDR S&P Homebuilders ETF, which tracks the sector, is down almost 16% since the end of June.
Fox News highlighted the flip side of the homebuilder story in coverage this week, noting that while Lennar missed estimates, Strategic Wealth Partners CEO Mark Tepper still names Toll Brothers as his top pick in the sector. That's a reminder that not every builder is bleeding the same amount, even as the group faces the same rate headwinds.
Berkshire's Logic: Buy When It's Cheap
Catherine Seifert, an analyst at CFRA Research, called the move a "classic Berkshire value play." Buffett's company built its reputation buying good businesses when the market has beaten the stock down, and Lennar fits that description on paper.
This isn't Berkshire's first rodeo in housing. The company already owns paint maker Benjamin Moore, roofing materials producer Johns Manville, and carpet maker Shaw Industries. It bought manufactured-home maker Clayton Homes for nearly $2 billion back in 2003. Seifert noted Berkshire has "a pretty significant presence" in the housing supply chain already.
Current Berkshire CEO Greg Abel, who took over from Buffett, is continuing that playbook rather than breaking from it. And Berkshire has the firepower to do it: the company was sitting on roughly $367 billion in cash at the end of June, according to CNBC.
The Case for Skepticism
There's fair pushback on treating this as a bullish signal for housing broadly. Berkshire buying a beaten-down stock is not the same as the housing market turning a corner. Lennar's own management is the one telling investors that affordability is deteriorating and its fourth quarter will be softer than expected. Nothing in the earnings report or the mortgage-rate data suggests the pressure is easing.
A value investor buying a cheap stock during a downturn is a bet that the stock price has overshot the fundamentals, not a claim that the fundamentals themselves have improved. Berkshire's history includes plenty of positions that took years to pay off, and homebuilders remain exposed to whatever the Federal Reserve does with rates next.
The key question: does Berkshire know something about a rate-cut path or housing recovery that the broader market doesn't, or is this a multi-year value bet that will look smart or dumb only in hindsight? Neither CNBC's report nor the securities filing itself spells out Berkshire's specific rationale beyond the size of the purchase. Investors will get their next real data point when Lennar reports fiscal fourth-quarter results, and when Freddie Mac's weekly mortgage-rate survey shows whether 7% is a ceiling or a floor.
Sources used for this briefing
This briefing was written by UBH's AI agent — these are the reporting inputs it draws on, linked so you can verify.


