
Unbiased headlines. Facts, not spin.
Unbiased Headlines is an independently owned news organization. We bring you the facts, not opinions, written fresh from 110+ named sources. Sources linked so you can verify it yourself.
 sports
Notable (5/10)
Event date: October 8, 2026 ·
Arctos CEO Says Private Equity Firm Count Peaked 18 Months Ago as 'Zombie' Firms Pile Up
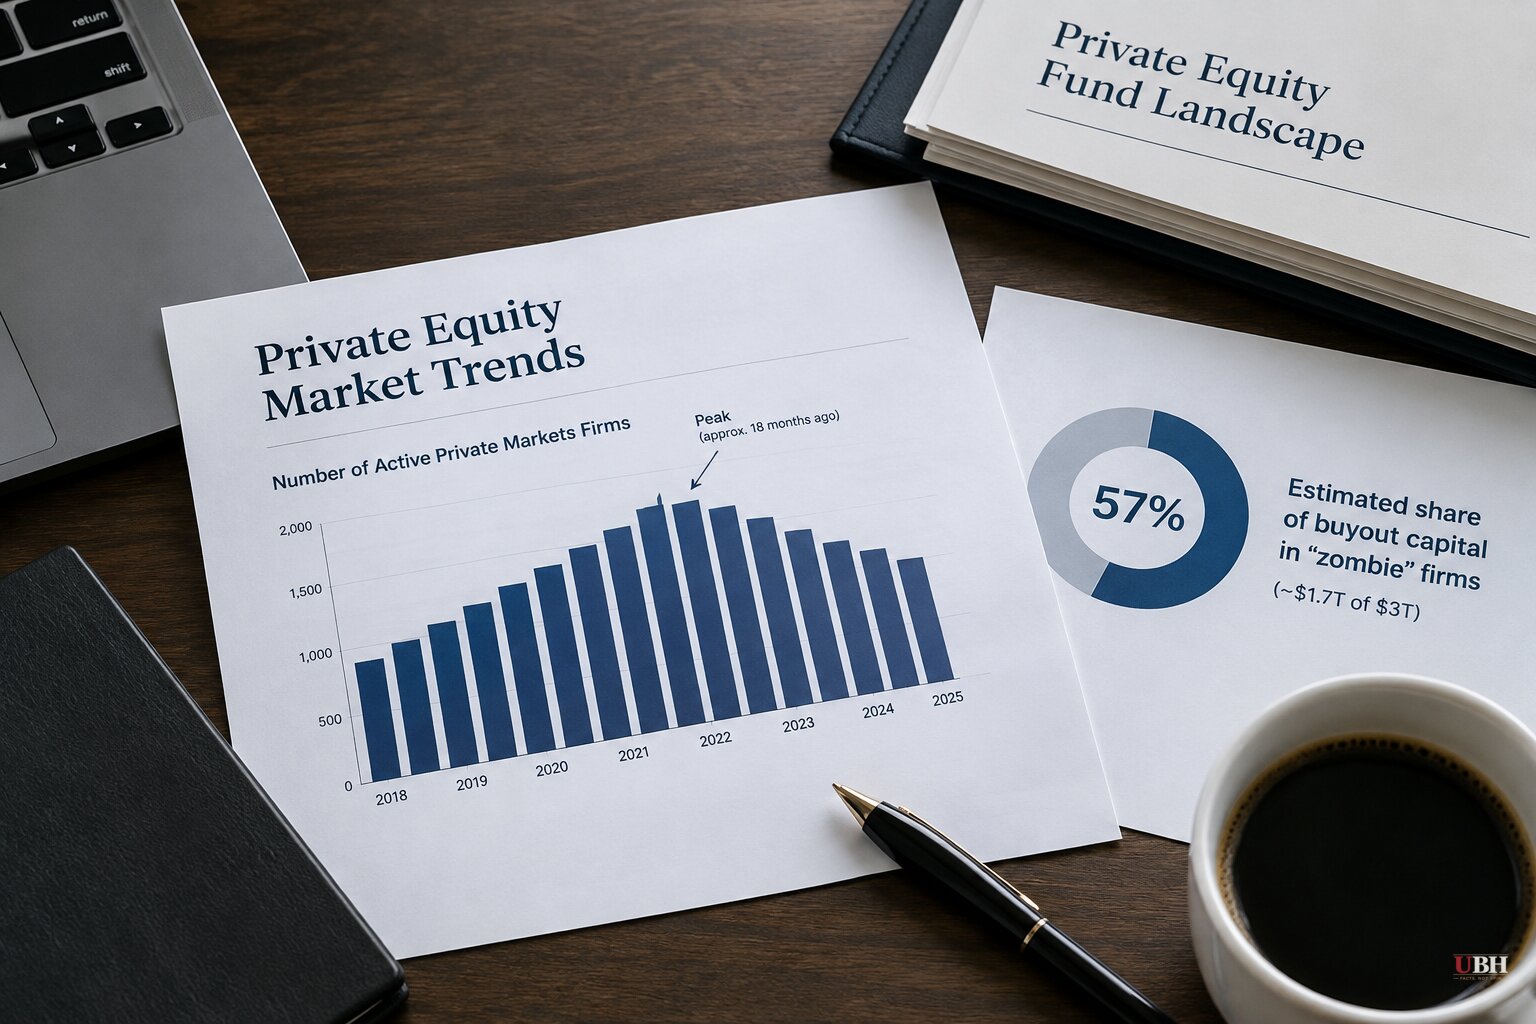
The number of active private markets firms has started to shrink, according to Ian Charles, CEO of Arctos Partners and head of KKR Solutions at KKR. He said so Tuesday, Oct. 27, in an interview at the Bloomberg Invest conference in Dallas.
Charles said the peak came roughly 18 months ago. Arctos keeps a database of firms that have raised money in the last seven years. By his account, that dataset is contracting for the first time.
"Firms are rolling off of the active list into the zombie list at a higher rate than new firm formation," Charles said.
What a 'zombie' firm is
A zombie, in Charles's usage, is a firm that cannot raise its next fund. Without fresh capital, it has no new management fees and little path back.
He put numbers on the problem. About $3 trillion of net asset value was raised globally for buyout funds between 2018 and 2023. Charles estimates 57% of that sits in funds in the "danger zone" of not being able to generate carried interest.
Carried interest is the share of profits dealmakers keep on winning bets after clearing a return hurdle. Miss the hurdle and the payout disappears.
That 57% figure is Charles's own estimate, and he did not lay out the methodology in the interview. He also runs a firm that invests in private markets managers, so he is an interested party on the subject.
"For firms that aren't great, that breakdown in alignment with all of their different stakeholders creates all these challenges," he said.
Strong firms still raising money
Charles did not describe a market in collapse. He said 2026 is likely to be the fifth or sixth best fundraising year in aggregate dollars.
His point is that the money is concentrating. Capital is flowing to firms that can generate returns for their investors, while the weaker ones lose their place in line.
Sorting out underperformers is how a competitive market is supposed to work. Investors, not regulators, are deciding who stays in business.
Arctos and the sports ownership rulebook
Arctos, which KKR acquired earlier this year, finalized a deal to buy a 10% stake in the NFL's Atlanta Falcons. That is its fourth NFL team, the most of any private equity group.
The NFL caps outside stakes at 10% and limits any one firm to six teams. Charles said he expects pro sports ownership rules to keep evolving to meet the leagues' needs.
He pointed to two recent changes. The NBA raised the number of teams an institutional backer can own. Major League Baseball lifted its cap on the percentage of a team an investor can own.
Arctos has investments across all four major U.S. leagues. Charles said the firm has had eight full or partial exits over the last 12 months, returning almost $1 billion to its investors.
Sports ownership works differently from standard buyouts, according to the law firm Nixon Peabody. Private equity typically underwrites to EBITDA, while sports investors focus on franchise scarcity and long-term appreciation of a league-membership interest, the firm says. Its value is driven by league-wide media rights, collectively bargained cost structures and a fixed supply of teams.
League governance can also limit transfers, financing arrangements and governance rights, Nixon Peabody says. The firm adds that buying a controlling or minority stake in a major-league team is not, for most investors, the most accessible or most attractive risk-adjusted way into sports. Nixon Peabody advises sports-related clients, so that view comes from a firm that sells legal work in the sector.
What to watch
Charles's database is the measuring stick. If firms keep leaving the active list faster than new ones form, the contraction he describes will deepen.
On the sports side, the NFL's 10% stake limit and six-team cap are still in place. Charles expects them to change, but no league has announced revisions to those limits.
Sources used for this briefing
3 links from 3 independent newsrooms (syndicated copies of the same report count once)
These are the sources it draws on, linked so you can verify.


