
Unbiased headlines. Facts, not spin.
Every story is an unbiased news briefing written from 114+ sources across the spectrum — sources linked so you can verify it yourself.
 finance
Notable (6/10)
Event date: October 5, 2026
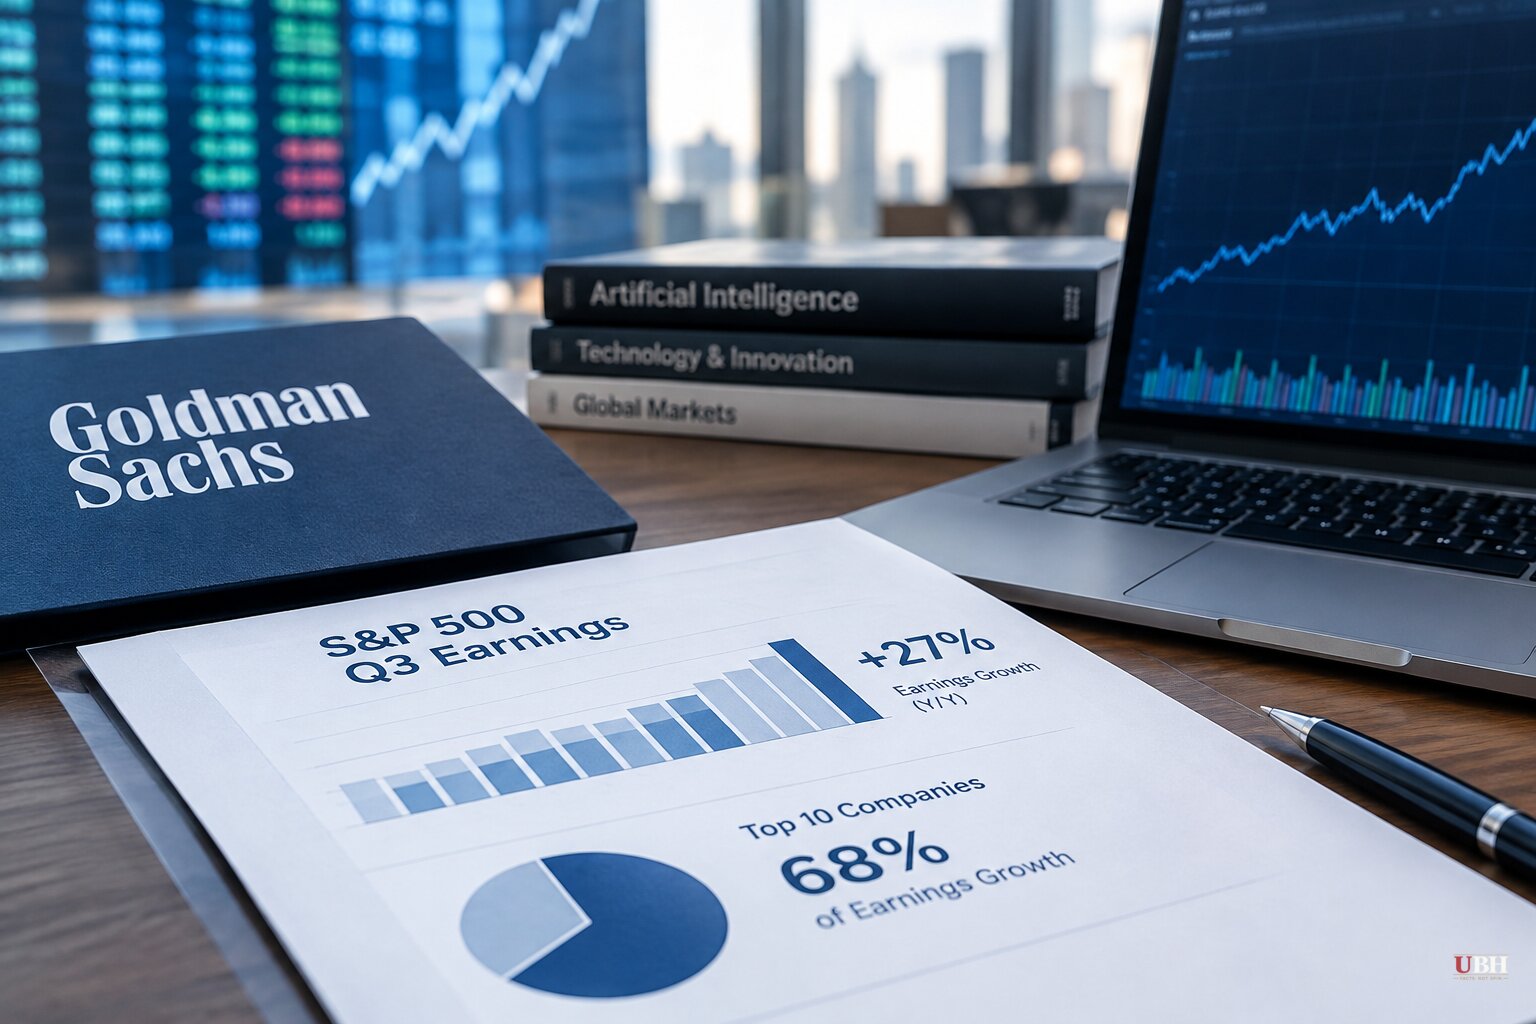
Goldman Sachs Expects 10 Companies to Deliver 68% of S&P 500 Q3 Earnings Growth
The S&P 500 is heading into third-quarter earnings season with profit growth that looks enormous on paper and is held up by very few companies.
Goldman Sachs strategist Ben Snider, in an Oct. 2 report, said consensus calls for Q3 earnings per share to rise 27% from a year earlier. That would be a slowdown from the roughly 33% growth Goldman recorded in Q2 once accounting distortions are stripped out. Goldman also expects most companies to beat consensus again. These are forecasts. The reports have not arrived yet.
Ten companies, two-thirds of the growth
Goldman's concentration numbers are the part to watch. The firm expects 10 companies to generate 68% of the index's Q3 earnings growth. Micron and Nvidia alone are projected to account for more than one-third.
By sector, information technology and energy together are expected to produce nearly 80% of the increase. AI infrastructure companies are projected to account for more than 50% of the growth.
Micron has already set the bar. It reported record fiscal 2026 results last week, and CEO Sanjay Mehrotra said, "we expect an even stronger 2027." Revenue grew 379% year over year, according to investor commentator Louis Navellier. Earnings growth was reported at roughly 1,000%, though the figure varies by account: 1,003% in one and 1,061.5% in another.
Other numbers vary by source too. FactSet's estimate for Q3 S&P 500 earnings growth is 29.1%, per Navellier, against Goldman's 27%.
The bull case
Navellier is bullish and says so. He argues that the big tech earnings are real and that the setup is strong. He wrote that Nvidia announced a $150 billion share buyback last week, which he called an all-time record, topping Apple's $110 billion program in 2024. He said Nvidia has not finished its earlier authorization, so it could now repurchase up to $235 billion of its shares. That is his figure, and Nvidia's own filings are the place to confirm it.
Navellier says Nvidia trades at 24.6 times forecast fiscal 2028 earnings, against 38.5 times for Apple. He projects Nvidia at $300 by year-end. That is a forecast from one analyst, not a data point.
What Goldman says fades
Goldman's own research is more cautious about how long this lasts. Snider estimates almost half of 2026 S&P 500 earnings growth traces to AI-related investment. Hyperscalers, including Amazon, Meta, Alphabet and Microsoft, are expected to spend about $800 billion on capital expenditures in 2026, up 94% from 2025. Goldman projects $1.2 trillion in 2027 and $1.4 trillion in 2028.
That spending comes with a bill. Goldman estimates depreciation will subtract roughly 5 percentage points from S&P 500 earnings growth in 2027, against an 11-point boost from continued AI capex. By 2028, depreciation could fully offset the earnings contribution from additional AI investment.
Two other boosts are expected to shrink:
- Memory margins. Memory producers are running gross margins near 80%, more than double historical levels. Goldman expects supply to stay tight through 2027 but margin expansion to slow. A return toward historical profitability could cut S&P 500 earnings by roughly 10%.
- Paper gains. Large technology companies booked about $150 billion of unrealized gains on private AI investments in Q2, equal to about 12% of S&P 500 EPS. Goldman expects more gains in the second half of 2026 but much less in 2027; removing that contribution entirely would be an estimated 8-point drag on 2027 earnings growth.
Q2 reported EPS growth of 51% year over year, against roughly 33% with distortions removed, shows how much of the headline number is not core operating profit.
Costs on the other side of the ledger
Memory is a profit center for Micron and a cost for everyone buying it. The Institute for Supply Management's September services report, relayed by analyst Peter Boockvar, put the prices-paid index at 74, up from 72.6 and the highest since July 2022. Seventeen of 18 industries reported higher prices. ISM respondents cited tariffs and fuel costs as the leading supply-chain problems, and memory products were up in price for the ninth straight month.
The services index itself slipped 0.5 point to 54.9, still well above 50.
Bonds are adding pressure. TheStreet's Doug Kass wrote on Monday that bond prices were falling and yields were at the high of the day. The VIX closed at 15.51. Kass added that long-standing relationships between stock prices, rates, valuations and market breadth no longer appear to be relevant. Seeking Alpha contributor Luca Socci describes the Q4 setup as fragile, citing multiple compression, rising yields and earnings concentrated in energy and semiconductors.
What comes next
Goldman's framing is that the real test is whether AI spending can spread into a broader earnings lift or whether the index stays dependent on a narrow group of winners. The first answer comes when the largest names report in the weeks ahead. If Micron and Nvidia deliver and the other 490 or so companies do not, the 68% concentration figure will have been the headline all along.
Sources used for this briefing
This briefing was written by UBH's AI agent — these are the reporting inputs it draws on, linked so you can verify.


